
A Message From Base Camp Trading
Hey Trader,
This certainly isn't going to win me any friends in the industry.
But I don't care.
For Black Friday, I'm practically giving away my proprietary "Snapback Indicator."
It's yours for just a single payment of $7. No strings attached.
When you see the Crash Alert, that's your cue to get out or go short.
When you see the Bull Run Alert, that's your cue to buy or go long.
Don't make another trade until you see this indicator in action. Best of all… I'm giving you LIFETIME access. Others paid $500 for this. But you're getting lifetime access to the Snapback Indicator for just $7.
Go here:
Black Friday Bombshell: "Snapback" Indicator For $7
In your corner,
Thomas Wood
Base Camp Trading
P.S. There's an unusual reason why I'm giving you such an outlandish discount on this incredible indicator. Full explanation here.
Further Reading from MarketBeat
Cerebras Q3 Results: How Much More Proof Does Wall Street Need?
Written by Thomas Hughes. First Published: 11/14/2026.

Key Points
- Cerebras Systems reported 70% core revenue growth in Q3, supported by accelerating cloud demand and new customers.
- The company raised guidance and expects continued growth as it expands data center capacity.
- OpenAI deployment delays, execution risks, and shareholder dilution remain concerns despite the improving outlook.
- Special Report: Trump’s third impeachment?
Cerebras Systems’ (NASDAQ: CBRS)Q3 results echo a message reflected across companies critical to AI: demand is rising for the leading hardware, software, and services that deliver value to hyperscalers. The industry has shifted from speculating about which technologies might prove best to focusing on the best, with forecasts pointing to several quarters of accelerating growth and sustained long-term strength.
CBRS faces company-specific headwinds, including dilution associated with its IPO and customer warrants. However, those concerns are being weighed against growing demand for Cerebras hardware, which delivers high-speed, cost-efficient inference. The product’s utility is reflected in results that beat consensus, as well as strong guidance and a backlog worth more than 100 times Q3 revenue.
Cerebras Is on the Verge of Explosive Growth
Cerebras Systems grew core revenue 70% in Q3, outpacing consensus by about 7 percentage points on strength from new and existing customers. Hardware sales fell compared with the prior year, but surging cloud and services demand offset the decline. Core cloud revenue, which excludes pass-through revenue and costs and accounts for non-cash charges, grew more than 270% to about 67% of revenue. The company expects this growth to accelerate in upcoming quarters.
Cerebras improved its core gross margin through scale leverage, but higher spending tied to its capacity ramp offset that improvement. Management expects spending to continue, but rising capacity and utilization could improve core margins and shorten the path to profitability.
Cerebras expects core revenue to grow about 40% sequentially to roughly $320 million, and the guidance may prove cautious. The company has another 700 MW of capacity under contract, supported by new wins with hyperscalers and neoclouds, including an unnamed top-three hyperscaler, as well as its backlog. In this scenario, Cerebras needs to execute on its capacity ramp and contractual commitments to deliver better-than-forecast results.
The new top-tier hyperscaler is a validating factor. Although the report didn’t name it, CEO Andrew Feldman later revealed that it was Microsoft (NASDAQ: MSFT), making Alphabet (NASDAQ: GOOGL) a notable hyperscaler without a publicly disclosed Cerebras partnership. Other relationships include OpenAI, Amazon (NASDAQ: AMZN), and Oracle (NYSE: ORCL), as well as a model-integration partnership with Meta Platforms (NASDAQ: META).
The takeaway is the scale of Cerebras’ demand: several major cloud providers and neoclouds have agreements to deploy or offer Cerebras technology, broadening its customer base. Management expects revenue to roughly triple next year, although projections for later years depend on continued execution.
Analysts Respond With Cautious Optimism
Analysts generally like what they see in Cerebras’ report, citing the backlog and capacity ramp as potential catalysts for the stock. However, they also expressed caution about execution, pointing to delays with OpenAI and the general risks of expanding high-tech manufacturing. The OpenAI delays are concerning, but CEO commentary offers some reassurance. Mr. Feldman says the delays are tied to land, construction, and power, rather than supply constraints or manufacturing hiccups. Sentiment remains intact, and consensus forecasts triple-digit upside as of mid-November. However, analysts have trimmed their price targets, some drastically, creating a headwind for the stock.
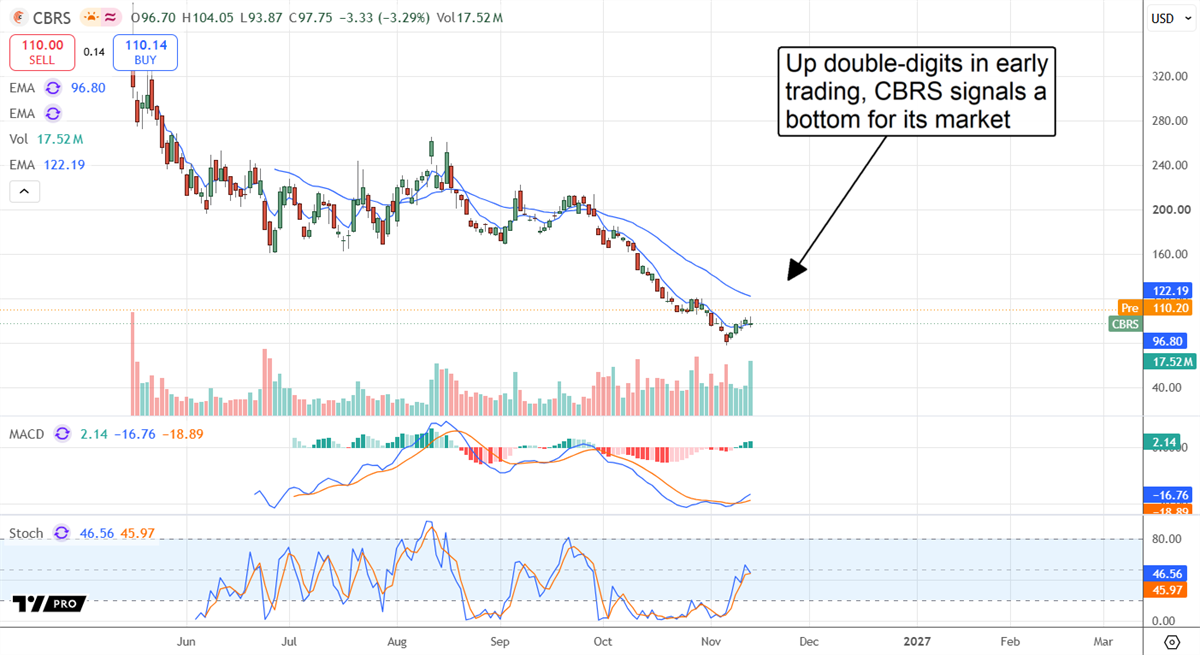
CBRS stock responded favorably to Cerebras’ report despite analysts’ revisions. Shares surged more than 10% in extended trading, suggesting a possible market bottom and the potential for short-covering over the next few months. Short interest was high ahead of the release, at more than 9%, which could lift the share price as short sellers cover. However, the relatively low 2.1 days to cover may limit the potential for a sustained squeeze. Other signs of market strength, a possible price floor, and rebound potential include bullish crossovers in the stochastic and MACD indicators, steadily increasing trading volume, and conspicuous volume spikes coinciding with the latest lows and pre-release price action—all possible signs of short covering.
Time is the biggest risk: the time required to ramp capacity, fulfill remaining performance obligations, and transition to profitability. The balance sheet suggests the company has a clear capital runway, with substantial cash and investments to support expansion, although spending requirements remain significant. The key catalysts are executing on the backlog and transitioning to profitability. Management forecasts core operating results near breakeven in Q4, while sustained GAAP profitability remains uncertain.
The market is right to treat this stock with caution given the execution risks, but it is wrong to treat it as a run-of-the-mill startup. Its product is validated, the company has revenue and signs of acceleration, and it has a path to near-term profitability. Long-term earnings forecasts suggest substantial upside potential, but the case for deep value depends on ambitious growth assumptions.
. |


