 A Message From Brownstone Research Former tech executive Jeff Brown, the man who picked Nvidia in 2016, before it jumped as high as 37,800%, just got inside a Cybercab, Elon Musk's new car that has no steering wheel or pedals… and what happens will shock everyone. Click here to see the details or read more below.
Dear Reader, In April 2026, Elon Musk announced he was partnering with Intel. The result? Shares took off… And were trading 177% higher just two months later. I believe Elon is about to announce a NEW partnership with this little-known company… To work on what he called "the most epic AI project in history." But you need to act fast… Because Elon has already approached this company. I believe he's going to make it official any day… Which should send shares higher than anyone can imagine. Click here to see the details. We have so much to look forward to, Jeff Brown
Founder & CEO, Brownstone Research
Additional Reading from MarketBeat.com
Garmin Raises Its Profit Outlook—Can the Stock Reach New Highs?By Thomas Hughes. Published: 10/29/2026. 
Key Points
- Garmin posted strong Q3 results with 12% revenue growth and raised full-year guidance above consensus, driven by gains in Outdoor, Fitness, Marine, and Aerospace segments.
- Analysts hold a Moderate Buy consensus on Garmin, and institutions own roughly 80% of shares, supporting a continued uptrend.
- The company maintains a healthy capital return program with free cash flow fully covering dividends and buybacks, backed by a debt-free balance sheet and growing equity.
- Special Report: Today's pick is on the house...
Garmin’s (NYSE: GRMN) profit outlook is strengthening, positioning the stock to sustain its upward momentum. The company's Q3 results reflected not only business strength but also increasing scale leverage. Looking ahead, its next-generation Auto OEM program with Mercedes-Benz (OTCMKTS: MBGAF), expected to launch in 2027, could provide another source of growth.
The only weak spot today is the Auto OEM segment, as Garmin winds down legacy programs in 2026 ahead of next year’s launch. Meanwhile, the company's other four segments are growing rapidly, driving cash flow and enabling healthy capital returns. Garmin’s capital-return profile is far stronger than that of the average dividend-paying stock. In Q3, capital returns, including share buybacks, were fully covered by free cash flow (FCF). The FCF payout ratio came in near 83%, a highly manageable level that leaves the distribution outlook intact. The dividend yields an annualized 1.4% as of late October. Buybacks aren’t impressive, but they offset share-based compensation and other dilutive actions, leaving shareholders in a stable position. Other key details include a pristine balance sheet with zero long-term debt, ample liquidity and improving equity, which is up 6.43% year to date. Garmin Outperforms in Q3, Raises Guidance and Bolsters SentimentGarmin posted a solid quarter, growing revenue 12% in Q3 despite weakness in Automotive. Revenue missed MarketBeat’s consensus by a slim margin, despite support from strength in Outdoor, Fitness, Aerospace and Marine, which grew 20%, 16%, 5% and 16%, respectively. In Outdoor and Fitness, smartwatches and wearables drove gains. Margin results were strong. Scale provided leverage at both the gross and operating levels, with gross margin up 420 basis points (bps) and operating margin up 500 bps, driving accelerated earnings growth. Operating income improved by 34%, nearly tripling the top-line gain; GAAP earnings grew 35%, while pro forma earnings increased 39%. Guidance was another strength and catalyst for the share price. The company issued full-year guidance above expectations and may have been cautious in its estimates. Revenue is expected to reach approximately $8.15 billion, with pro forma earnings per share (EPS) of $10.80 versus the $10.13 consensus. Reasons to believe the guidance is cautious include a forecast slowdown to low-double-digit growth, traction from new products ahead of the critical holiday shopping season and the impact of the Auto OEM wind-down, which appears to be fully accounted for. Analysts See Upside for Garmin, But Risks RemainAnalyst consensus at the end of October rated Garmin a Moderate Buy. The Buy-side bias is about 45%, and no Sell ratings are logged. While the consensus price target offers only modest upside, it would still be sufficient to push the stock to a new high. A move to fresh highs would confirm the uptrend and open the door to further gains. In this scenario, GRMN’s share price could continue trending higher, reaching the high end of the target range over the subsequent 12 months. Institutions are bullish on the stock, reflecting confidence in its outlook by owning 80% of shares. They have been accumulating shares in 2026, limiting downside risk, as they are likely to buy on dips. The biggest sell-side risk is short interest, which has been creeping higher but remains minimal. Short interest is 1.2% of the float and likely represents hedging and risk management rather than outright bearish activity. At such a low level, it is unlikely to create a headwind for the stock. Q3 and early Q4 stock price action reflects a market top, but one within an uptrend, making the pullback an entry point for trend-following investors. Price action was favorable after the release, showing support within the consolidation range and the potential to advance in the coming quarters. Indicators such as MACD and stochastic align with this outlook, with stochastic showing a bullish crossover and MACD positioned to do the same. 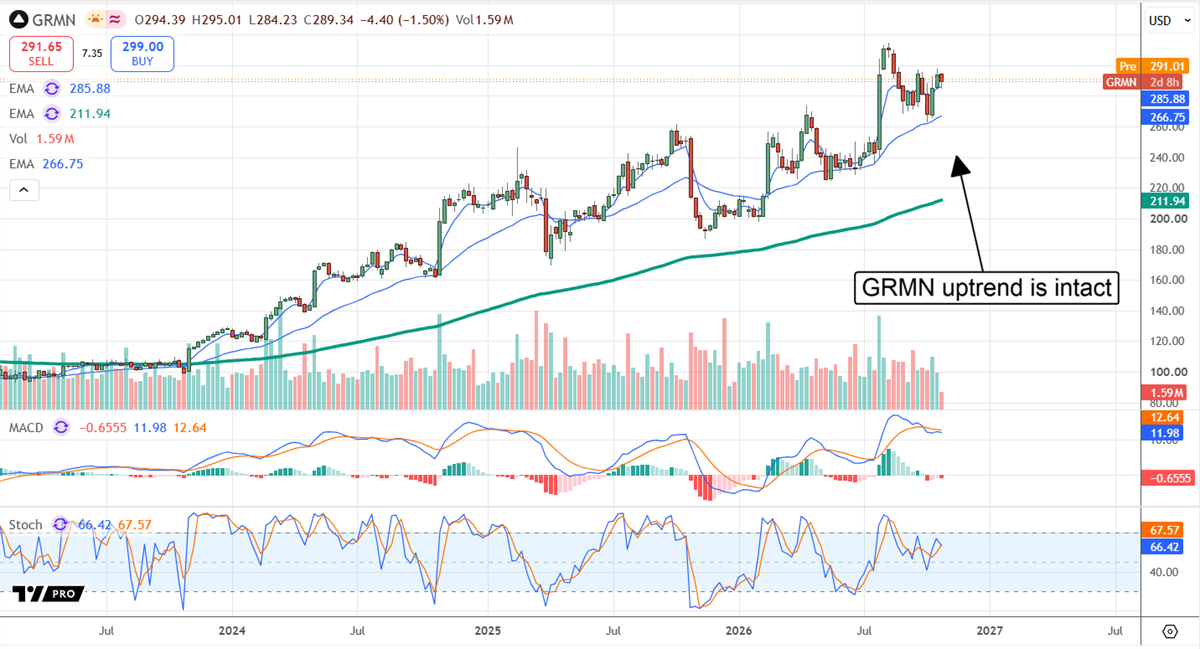
One risk is valuation: Garmin is somewhat expensive, trading at about 28 times its current-year EPS outlook. However, the current valuation likely reflects expectations for steady growth, cash flow and capital returns. Other risks include supply-chain exposure, which does not appear to be a problem currently, and competition. Wearables and consumer devices are a hot market, as are the OEM aerospace and defense industries, and competition is fierce. Investors should not discount Garmin’s moat: It is the leading manufacturer in most of its markets, as demonstrated by the seven quality and satisfaction awards it received during the quarter. . |


No comments:
Post a Comment