 A Message From Golden Portfolio Dear Reader, I’m a 30 year veteran gold analyst… And today, I want to tell you about one of the world’s best gold mines. This mine contains some of the highest grade ore found anywhere on the planet. But that’s not even what excites me about this play… Because this company has a very unique, high-yield dividend policy… Which is virtually unheard of in the mining industry. And I’ve put all of the details together into a single report. If you feel like you missed out on the early part of this bull market - this report is exactly what you need to get back on track. Buy this security now and you can collect up to 10% yields AND get the upside of one of the world’s best gold mining operations. Best, Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio P.S. The only catch: this security’s yield is already capturing the attention of global investors. Among them: the Rothschilds, Vanguard, and BlackRock. This is your chance to join them before it's too late.
Bonus Article from MarketBeat
AI Panic Hit Tech Stocks—But NVIDIA’s Growth Engine Is IntactReported by Thomas Hughes. Posted: 9/16/2026. 
Key Points
- Despite calls to slow AI model advancement, infrastructure demand remains strong, with backlogs and capital expenditure plans expanding significantly across hyperscalers in Q2.
- NVIDIA maintains a nearly 97% Buy-side analyst consensus with no Sell ratings, and its consensus price target implies more than 50% upside from current levels.
- Inference workloads, led by companies like Advanced Micro Devices, are poised to accelerate data center buildout as AI infrastructure shifts from training toward profitable monetization.
- Special Report: A Wall Street Veteran's Weekly Options Strategy Explained
AI leaders shocked the world by calling for a slowdown in AI’s advancement and increased regulation. The news triggered a sector-wide drawdown, raising the risk of a deeper correction, but short sellers shouldn’t get their hopes up. As concerning as this may seem to AI investors, a slowdown in AI’s advancement is unlikely to affect the infrastructure buildout. For the market, more advanced AI models are not the primary issue. Labs such as OpenAI and Anthropic already have highly capable—and potentially dangerous—versions. What matters is the infrastructure needed to deploy practical AI across the enterprise landscape.
The market is getting this wrong: safety and capacity aren’t the same thing. AI demand is not collapsing. Q2 results from NVIDIA (NASDAQ: NVDA) to Salesforce (NYSE: CRM), and nearly every AI-capable company in between, point to accelerating infrastructure demand. In this scenario, September’s price weakness represents a good opportunity to buy these stocks, with catalysts for further gains still ahead. The AI Boom Hasn’t Really Boomed (Yet)Key details for investors to watch include backlogs, utilization rates, persistent pricing power and the potential for capital expenditure (CapEx) relief. Q2 backlogs expanded at a historic pace, increasing by triple digits at Alphabet (NASDAQ: GOOGL), Dell (NYSE: DELL) and Super Micro Computer (NASDAQ: SMCI). Critical players such as Oracle (NYSE: ORCL), now ubiquitous across cloud instances regardless of the hyperscaler, saw backlogs grow to more than $650 billion. Meanwhile, neoclouds such as Nebius (NASDAQ: NBIS) reported even larger increases, with Nebius’s backlog growing fourfold. CapEx plans among the leading hyperscalers total more than $700 billion, underscoring the scale of current spending. Utilization rates matter because they are near 100%, even for older, legacy technology. The takeaway is that technology transitions from model training and advanced computing to inference as it ages, providing a long runway for cash flow and asset utilization. This is a foundational factor in NVIDIA’s ability to securitize its GPUs, enabling institutional investors such as retirement funds to invest in the resulting cash flows. The catalyst for stock price gains will be the monetization of existing assets, which coincides with improved profitability. Hyperscalers dialing back ultra-expensive frontier-model development could free up cash flow, removing the primary hurdle facing stock prices today. The upfront cost of AI infrastructure is significant, impairing cash flow and profitability for many AI-related companies. AI CapEx Fears Haven’t Derailed the Infrastructure TradeQ2 reporting was spectacular, with results significantly outpacing consensus estimates across the board. However, analysts remained skeptical of CapEx plans and a rapidly differentiating market, causing stocks to move in different directions. For now, AI infrastructure names, including NVIDIA, remain the big winners because they are the focus of current spending. Wedbush pointed out that the buildout is moving slightly faster than adoption, which is a root cause of concern. For investors, the takeaway is that slowing spending on AI models could improve profitability while freeing up cash to meet existing CapEx plans. Wall Street Keeps Raising the Bar for NVIDIANVIDIA is the most important stock in AI today, providing the core infrastructure and software that make the technology possible. Its analyst trends are as strong as they could be. MarketBeat shows coverage increasing month over month, along with a firm Buy consensus rating and nearly 97% Buy-side bias. Currently, the company carries no Sell ratings, and the consensus price target implies more than 50% upside. The price-target trend is significant, as revisions in August and September have pushed the consensus higher. The high-end target places the stock at $515, representing more than 100% upside, and even that forecast may prove conservative. Valuation metrics suggest NVIDIA is 50% undervalued today based simply on its price-to-earnings (P/E) multiple. The stock is trading in the low 20s, compared with its historical mid-30s range. 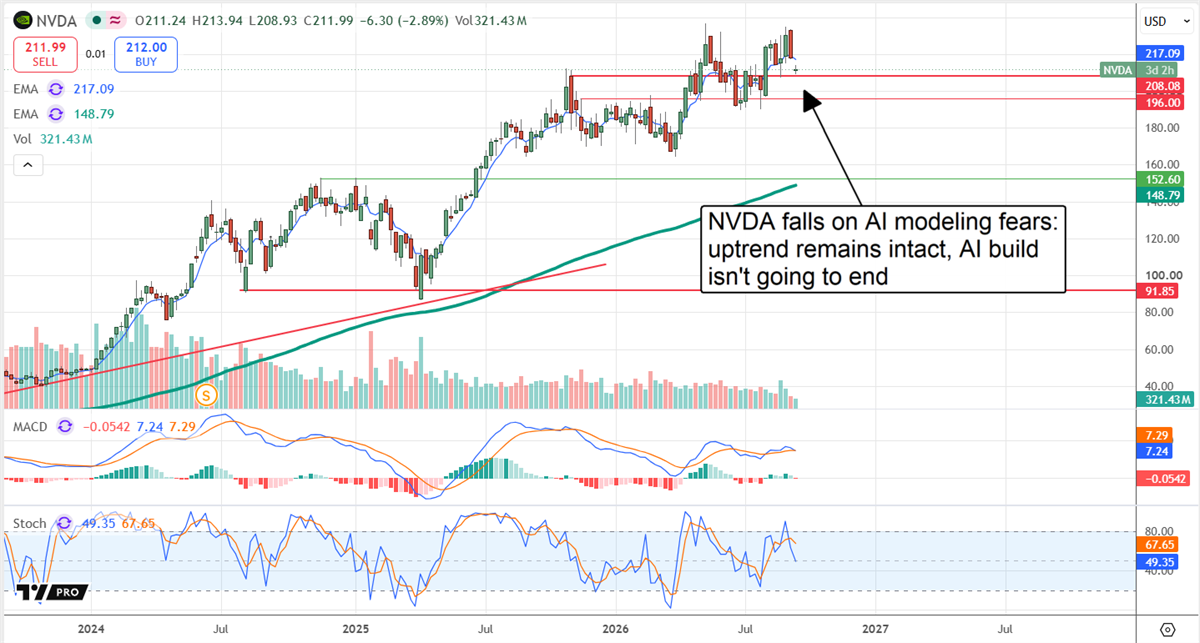
Longer term, the stock is trading at pennies on the dollar relative to its potential—approximately five times the five-year outlook—suggesting it could rise by 400% to 600% over the coming years. The Inference Boom Is About to HappenInference is accelerating today, heading toward a boom that Advanced Micro Devices (NASDAQ: AMD) will help unleash. Its Helios racks provide hyperscalers with numerous benefits, including greater inference speed, lower costs and improved profitability. Investors should remember that model training represents the “upfront” cost of AI, while inference drives back-end monetization. With this in mind, we can expect the data center buildout to continue at full speed, if not accelerate, over the coming quarters as AI inference reaches critical mass. The biggest risks for AI are bottlenecks in GPU and memory supply, as well as constraints involving energy and water. These factors are slowing the buildout but also creating opportunities. Companies such as Vertiv (NYSE: VRT), Bloom Energy (NASDAQ: BE) and AirJoule (NASDAQ: AIRJ) provide technologies that help overcome these hurdles and enable data centers to operate with minimal impact on local communities. Another risk involves the upcoming elections, which are likely to serve as a referendum on AI. The outcome will have far-reaching ramifications but is unlikely to end the buildout. Established AI companies could benefit from increased regulatory oversight, as it may widen their competitive moats by making it harder for new AI labs to enter the market and reducing the risk of disruption. If increased regulation does not materialize, these companies will have free rein to continue building their city-sized supercomputers. . |


No comments:
Post a Comment