 A Message From Profits Run If you still haven't downloaded my "Safe Trade Options Formula" book... ...please take a few seconds and download it right now before your new temporary download link expires. I eventually plan to charge for this book, so do yourself a favor and download it now... That way, no matter how much it is in the future, you'll have a copy on your computer already. Make sense? FREE: Safe Trade Options Formula << Download Now Good Trading,
Bill Poulos p.s. Go here to save a copy of my "Safe Trade Options Formula" book to your computer before I start charging for it.
Exclusive Story
Insiders Are Selling These 5 AI Stocks—Should You Worry?Author: Thomas Hughes. Posted: 10/26/2026. 
Key Points
- Insider selling across CoreWeave, Arista Networks, Dell, Snowflake and NVIDIA does not necessarily signal weakening fundamentals or bearish outlooks for these AI-linked stocks.
- CoreWeave faces the most risk due to heavy debt and interest-rate exposure, though analysts still rate it a Moderate Buy with substantial upside.
- Analysts remain broadly bullish on Arista Networks, Snowflake, and NVIDIA, citing strong fundamentals, growing AI demand, and significant price target upside.
- Special Report: Pentagon Eyes 75-Year Rare Earth Deal With This Nasdaq Company
The AI trade faces headwinds, and none may be as alarming as insider selling. The question, however, is what other forces are at play and how they affect the stock price outlook. While insider selling can be a headwind, it isn't always a red flag. If stock prices are favorable, analysts and institutions are supportive, and fundamentals are strong, insider selling may be nothing more than a detail. CoreWeave Insiders Drive Shares to Long-Term LowsCoreWeave (NASDAQ: CRWV) insiders have been selling shares for several quarters, with founders and early investors taking advantage of high share prices to trim their holdings. Key details include more than 20% insider ownership tied to founding executives and continued selling in Q4 2026. With shares at long-term lows, insider sales are salt in an open wound, regardless of their nature.
The risk with CoreWeave, however, isn’t so much insider selling as it is debt. Among leading neoclouds, the company is particularly exposed to interest rates, and the risks are mounting. Already in junk status, the company faces an incredibly high cost of converting its backlog into revenue, weighing on its outlook. Analysts have been trimming their price targets, capping gains. However, 36 analysts rate the stock a consensus Moderate Buy, with approximately 125% upside to the average price target. Given the oversold price action, a positive catalyst could trigger significant upside. 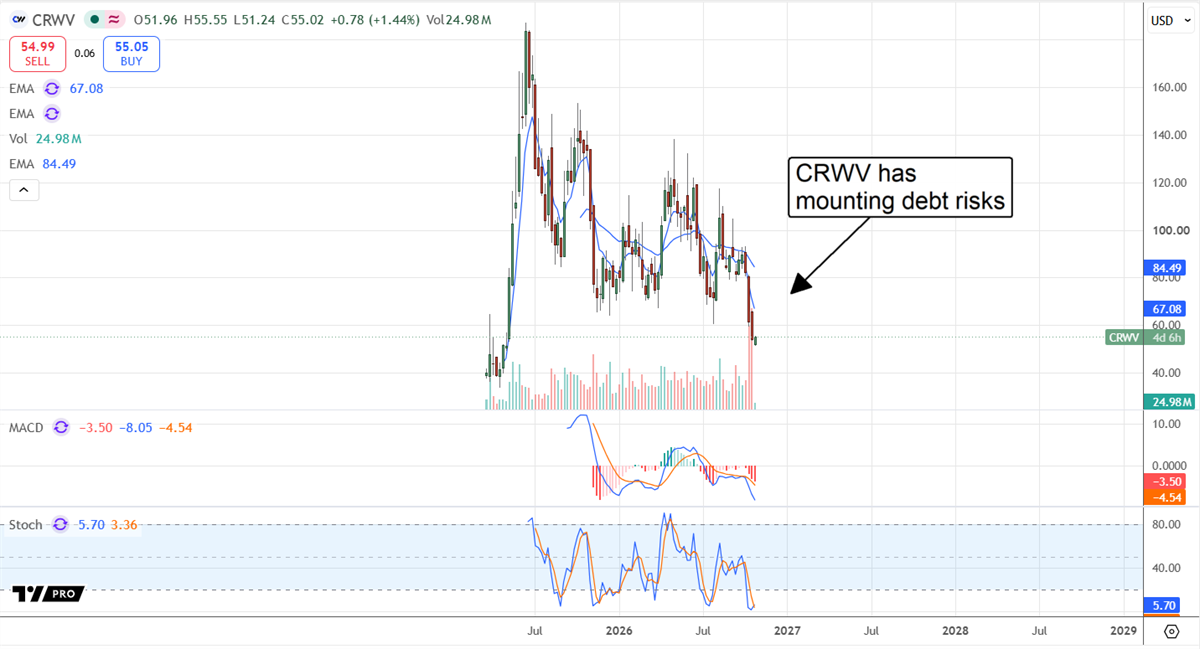
Arista Networks: The Fabric of AIArista Networks (NASDAQ: ANET) is critical to AI infrastructure because of its Ethernet switches, routing, and fabric technologies. Once a relatively simple layer of the technology stack, these technologies are now essential for high-speed, high-efficiency operations. The shift has put ANET products in high demand, and the stock price is rising. This gives insiders an incentive to sell, and they are doing so en masse. InsiderTrades tracks Q3 sales by the CEO, CFO, COO, and CTO, along with several directors. The caveat is that the sales were primarily made under prearranged plans, and the company's fundamental story is unchanged. Analysts rate ANET a consensus Buy because of its growing importance. The company is helping challenge NVIDIA’s (NASDAQ: NVDA) InfiniBand dominance, opening the door to a wider range of choices based on open standards. The consensus price target forecasts more than 30% upside, and institutions are accumulating shares. 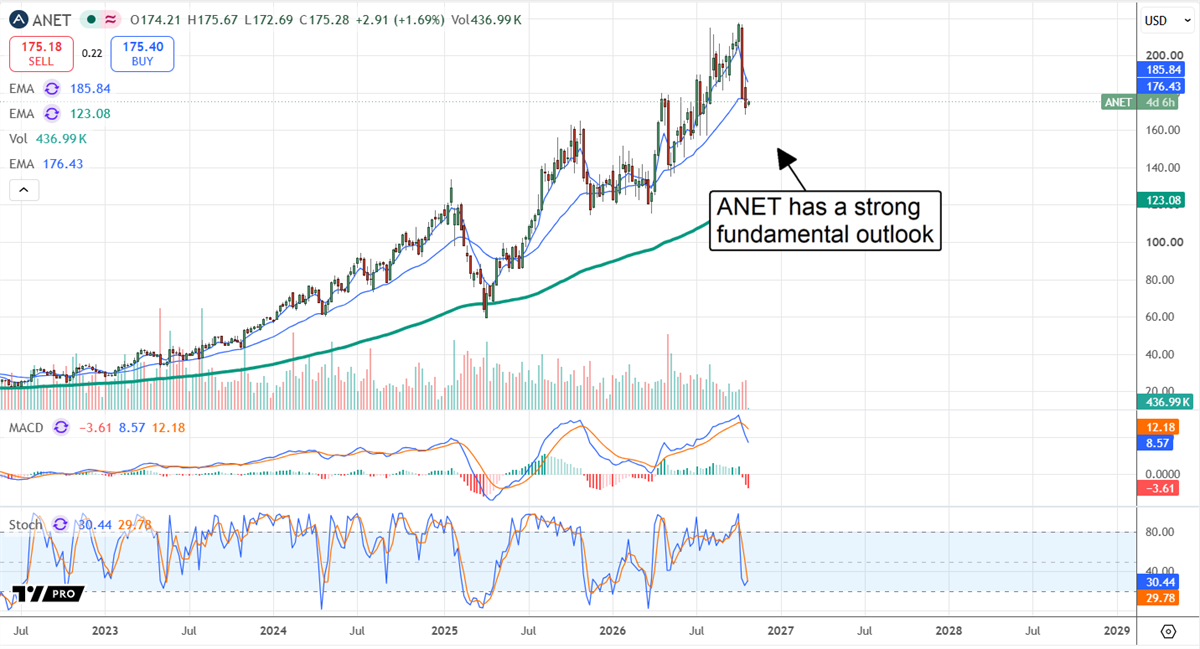
Dell: Early Investors Monetize Their InvestmentDell’s (NYSE: DELL) insiders are selling for a good reason: the stock is up more than 250% this year, providing an irresistible opportunity to monetize their shares. The primary seller is Silver Lake Partners, which has been liquidating its position for several quarters. Selling is likely to continue, potentially capping gains. DELL shares peaked in early October and are now in correction territory. The initial decline was substantial, at more than 25%, suggesting an extended consolidation with the risk of a deeper pullback. Institutional activity has also been mixed, with the group distributing shares on balance in early Q4. 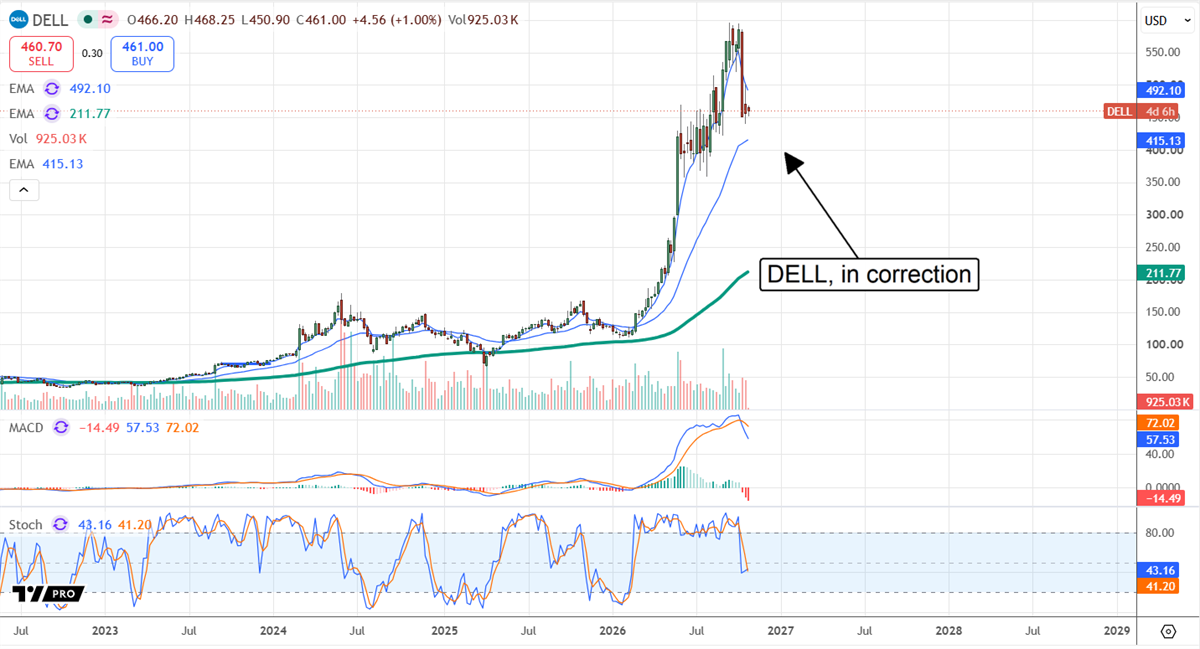
Snowflake: The Melt-Up Isn’t Over YetSnowflake’s (NASDAQ: SNOW) stock price is in melt-up mode following a misinterpretation of the AI SaaS apocalypse. The late-2026 narrative is that agentic AI doesn't erode demand—it drives it—and the business is performing at the high end of expectations. Insiders who are selling include numerous directors and junior executives with years of tenure and shares to sell. The offset is that analyst trends remain bullish, with coverage increasing, a bullish bias to the Moderate Buy rating, and about 25% upside. Institutional trends are also bullish. Activity is subdued compared with the prior year, but buying outweighs selling. Snowflake's primary growth catalyst is its transition to an agentic AI platform and a consumption-based model. Because the company operates on a consumption basis, continued growth depends on attracting new customers and expanding usage among existing ones. 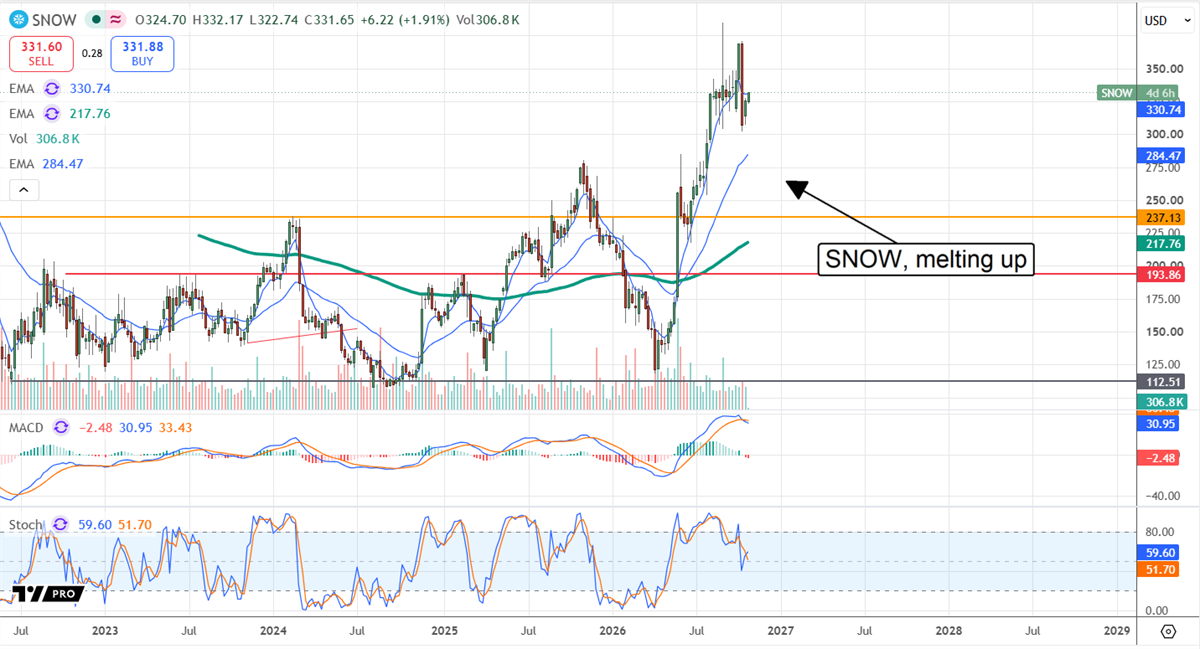
NVIDIA: The Center of AI Cash FlowMost AI spending is funneling toward NVIDIA, its GPUs, full stack of products, software, and services, making it the single most important AI stock. The company looks poised to more than double in value over the coming years, with growth underpinned by an expanding ecosystem that includes physical AI and robotics. Insiders sold NVDA stock in Q3, including directors, an EVP, and the CFO, but investors shouldn’t worry too much. Overall selling is down, and the fundamental outlook is unchanged, though risks remain. The biggest risk is capital and the time it takes to monetize backlogs, which has strained the entire industry. Spending plans are likely to remain unchanged, but headwinds will persist until monetization becomes more evident across the AI ecosystem. When that happens, capital flows will depend less on balance sheets or third-party financing, allowing risk-on sentiment to regain control. Analysts rate NVIDIA a consensus Buy and see the stock advancing 50% within 12 months. 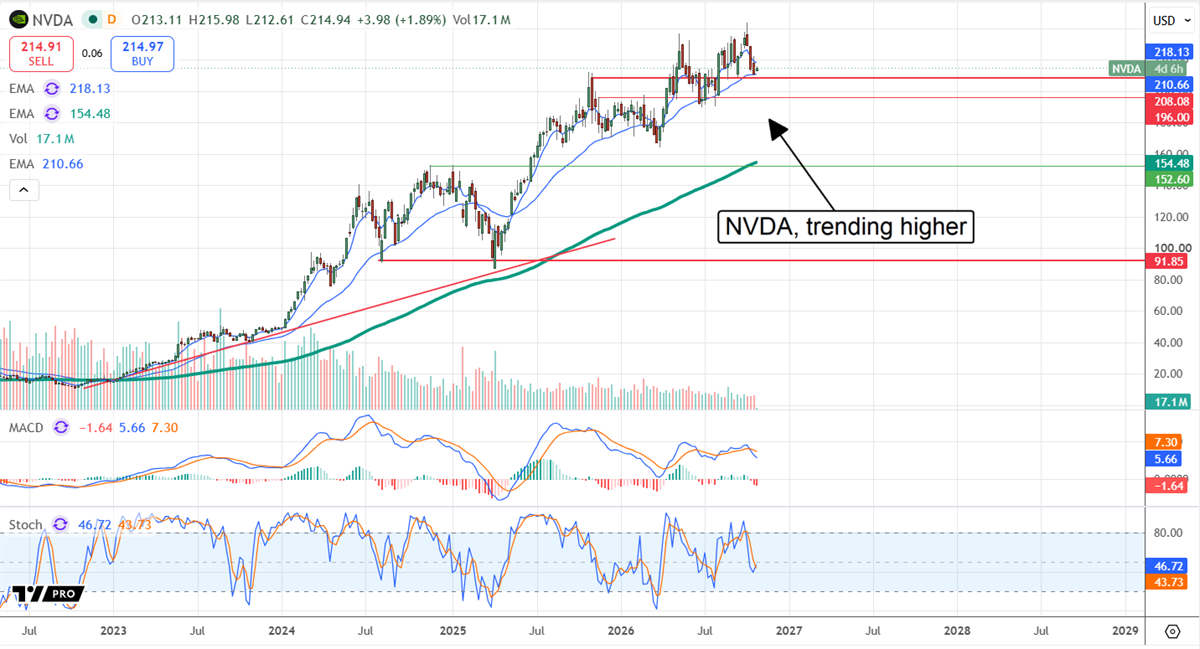
. |


No comments:
Post a Comment