 A Message From Behind the Markets Dear Friend, Watch what the institutions are doing, not what they're saying. Bank of America increased its stake in one small gold company by 139%. Jane Street, one of the most sophisticated trading firms alive, by 159%. Millennium by 122%. And one value fund, Kopernik Global, made it their single largest holding. They own roughly 8% of the entire company. The company doesn't even mine. It owns the rights to an 88 million ounce deposit, one of the largest on earth, with government-built roads and power already running to the property and permits that never expire. Market cap: about $4 billion. Value of the metal in the ground at today's prices: hundreds of billions. The institutions did this math quietly, over months. You get to do it this afternoon. Name, ticker and the full file here >> "The Buck Stops Here," Kelly Maguire
Behind the Markets
Just For You
Insiders Signal Deep Value In DICK’s Sporting GoodsAuthored by Thomas Hughes. Date Posted: 9/21/2026. 
Key Points
- Insider buying has picked up sharply after DICK’s Sporting Goods’ post-earnings sell-off, offering a notable counterpoint to weaker guidance and Foot Locker concerns.
- The longer-term opportunity increasingly depends on whether DICK’s can use its technology, customer data and retail ecosystem to extract more value from Foot Locker.
- Analyst caution and near-term margin pressure remain significant hurdles, but the lower valuation and roughly 4% dividend yield have changed the risk-reward setup.
- Special Report: Jensen Huang Calls This Machine a Technology Miracle
Insiders are signaling deep value in DICK’s Sporting Goods (NYSE: DKS), with a handful of directors buying shares in early Q3. The purchases are not only counter to the trend but also a response to the deeply discounted share price. DKS shares imploded following the Q2 miss; however, the market is mispricing the opportunity. While headwinds exist, this isn't a retail turnaround; it’s an aggressive ecosystem expansion underpinned by technology and, more importantly, a vast pool of data on athletic shopping habits and the revenue and earnings power it can generate. The hurdle today is the shoe segment and, specifically, integrating Foot Locker and realizing its potential. The pain is store-count rationalization, compounded by consumer headwinds; the opportunity is to expand DICK’s Sporting Goods, traditionally a big-box retailer, into niche urban markets in a targeted way. This would provide athletes with what they’re looking for, along with the accessories to go with it. Foot Locker also provides real estate, making this a land grab as much as anything else, along with entry into a coveted demographic: fashionable urbanites. Additional benefits include cross-selling and omnichannel integration. Insiders and Institutions Reflect Confidence in DICK’s Long-Term Opportunity
Insider buying is noteworthy because of the timing and the individuals involved, which include industry insiders and tech titans. It is also notable because they didn’t need to make these purchases. Insiders, including family holdings, account for about 30% of ownership and are reinforced by a strong institutional presence. In this scenario, insider buying can trigger market inflows and drive a reversal. Institutions likewise own a significant amount, with total holdings approaching 90%, and the group is accumulating. InsiderTrades data reveals that activity spiked to record levels in Q3 as DKS price action fell to long-term lows. Valuation is a hurdle today, but execution can overcome it. Trading at approximately 11.5x to 12x its current-year outlook, the stock aligns with long-term trends but fails to price in the forecasts. Analysts expect the DICK’s-Foot Locker integration to unlock modest but sustainable revenue growth, compounded by steadily improving margins. In this scenario, DKS shares trade around 5x the six-year outlook, suggesting 100% upside from current levels—and that’s if the forecasts are correct. Assuming DICK’s progresses its strategy and consumer headwinds ease, revenue and earnings growth will outperform estimates, setting the stage for earnings growth to amplify the valuation-based upside. If headwinds clear and the market reprices DKS to align with peers, which trade in the high teens to high 20s, upside potential more than doubles. Analysts Send DICK’s to Long-Term Lows: Can Keep Price Depressed in 2026Analysts present another hurdle for share prices, as trends reflect caution, with numerous downgrades and price-target reductions catalyzed by the Q2 release. That caution is reflected in the consensus rating: Hold across 23 analysts, with 11 Buy, nine Hold and three Sell ratings. While low-end targets put DKS in the $100 to $110 range, the consensus is closer to $167, aligning with the midpoint of a trading range and representing more than 35% upside from the critical support level. The likely outcome is that DKS reverts to the middle of its range; the only questions are when and what comes next. 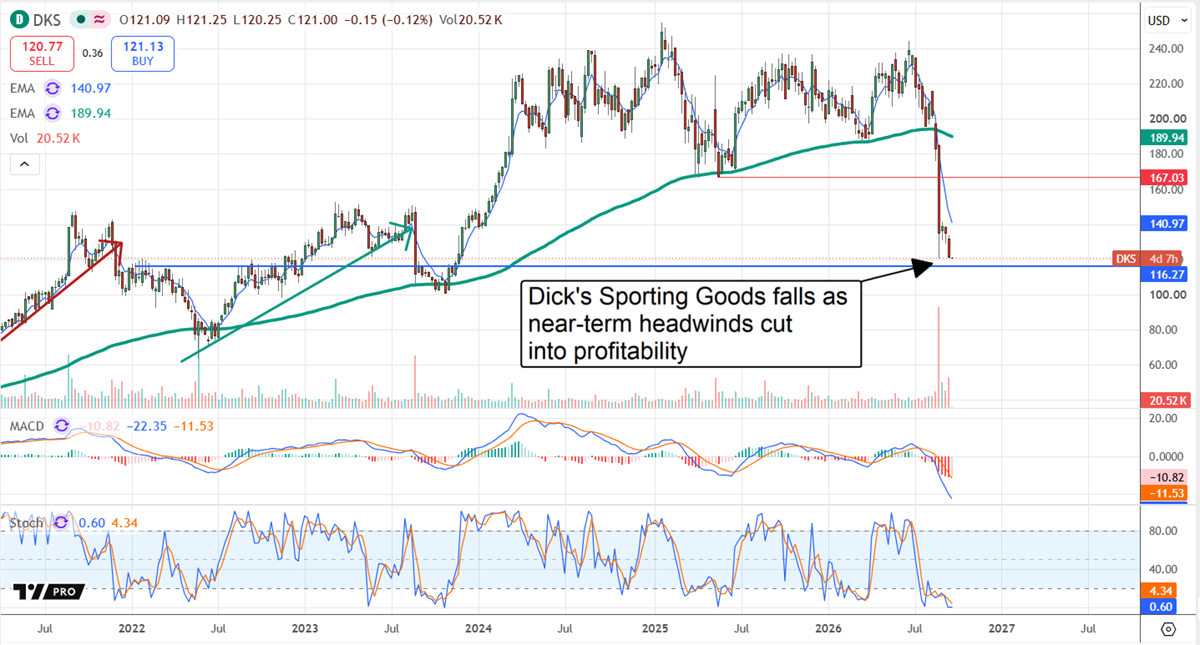
Critical support is just above $115. The technical risk is that DKS's initial bounce was very weak despite the high volume, suggesting that a dead-cat bounce is in play. The term assumes that even a dead cat will bounce if it hits the ground hard enough, and such a bounce can lead to lower prices or stagnation. Lower lows aren’t expected, given that results missed expectations but weren’t bad and still offer opportunities for growth, margin improvement and sustained capital returns. Stagnation is a real risk; DKS shares can wallow at these lows indefinitely if upcoming results don’t reinvigorate market appetite. DICK’s dividend is substantial, yielding approximately 4% with shares at mid-September lows. The payout is reliable but carries some risk, as margin pressure remains and free cash flow hasn’t been sufficient. The likely outcome is that dividend growth slows in the coming year but doesn’t disappear, then accelerates the following year. The more pressing concern is the impact on share buybacks, which have slowed, and the share count, which is up. The caveat is that the increase in the share count is tied to the Foot Locker acquisition, while buybacks, although slowed, continue to reduce the share count each quarter. DICK’s Q4 results are likely to be a catalyst. The company expects meaningful comparable-sales improvements as early as Q4, with structural margin recovery beginning in early 2027 and progressing throughout the year as restructuring concludes. Analysts forecast another quarter of solid growth, offset by margin impairments. . |


No comments:
Post a Comment