
A Message From Paradigm Press
Dear reader,
For the last few months, my team and I have been tracking some incredible activity across Elon Musk's most secure facilities.
And we have obtained shocking new drone footagethat has finally shed some light on what is going on:
Only a short time ago, this site was covered in thousands of trees. In a matter of weeks, at a pace almost no other company on Earth could match, all of it was cleared to make room for a single, groundbreaking new factory. It is already under construction.
What happens inside is something Elon is quietly calling his "infinite money glitch."
It sounds crazy to say out loud.
But if Elon succeeds, this factory could set off a snowball of wealth unlike anything the world has ever recorded.
And once that snowball begins to roll, it will be almost impossible to stop.
Based on my research, it could go live as soon as January 27.
I believe what is happening inside this factory is the most important story I have ever covered.
I put everything into a short presentation: what the "infinite money glitch" is, how much newly created wealth could be up for grabs, and how to take advantage of this opportunity before the deadline.
Watch it now. Because after January 27, the whole world could catch on to what’s inside.
Regards,
James Altucher
P.S. I’m giving away a free report to anyone who watches this presentation today. It details Elon’s Musk’s unprecedented trillion-dollar compensation package and identifies the companies he NEEDS to hit his incentives. Just click here to watch the free video, and I’ll show you how to claim it. No credit card needed.
Special Report
Amkor's Mobile Business Is Slowing, But Its AI Ambitions Aren't
Author: Thomas Hughes. Posted: 10/28/2026.
Key Points
- Amkor's weak Q3 results stemmed from declining smartphone demand, not from any slowdown in its growing AI-related business segments.
- Computing, automotive, and industrial segments grew to 48% of net revenue, reflecting a shift toward higher-margin AI-driven demand.
- Despite weak guidance, AMKR stock appears oversold and undervalued, with technical indicators suggesting a potential rebound toward consensus price targets.
- Special Report: A New Independent “Federal Reserve” Has Just Emerged in America
Amkor Technology's (NASDAQ: AMKR)Q3 results left something to be desired, but investors shouldn’t mistake weakness in its mobile business for weakness in AI. While AI is central to Amkor’s outlook, its near-term challenges are concentrated in smartphones. Mobile accounts for as much as 45% of revenue, depending on the quarter, and industrywide headwinds are expected to linger for years.
Wireless carriers have traditionally offered steep discounts on new phones to attract and retain customers, encouraging frequent upgrades.
Verizon (NYSE: VZ) is among the carriers moving away from that strategy and focusing instead on service quality and customer satisfaction. Phone upgrades are plunging across the industry, including a 20% decline for VZ in Q3, as mobile consumers hold on to their phones for longer. This trend is reducing demand for new smartphones and, in turn, for the semiconductor packaging services Amkor provides.
But it’s not all bad news. Amkor’s mobile business is likely to normalize over time, becoming a legacy business that may or may not see a resurgence in the future. Meanwhile, the AI industry is booming, helping offset the decline in mobile.
AI and related industries, including automotive and industrial, are growing at a robust double-digit pace and are expected to remain strong in the coming quarters. Growth could accelerate as the push for advanced technology and capacity expansion continues.
To capitalize on that demand, Amkor is expanding its operations with support from partnerships with NVIDIA (NASDAQ: NVDA), Apple (NASDAQ: AAPL), and Advanced Micro Devices (NASDAQ: AMD). These investments are helping cement its role as a critical player in AI infrastructure by easing semiconductor production bottlenecks and increasing capacity to meet growing demand.
Amkor's Mixed Q3 Results Reveal a Shift Toward AI
Amkor had a tough quarter, with weakness in the communications segment offsetting strength elsewhere. Revenue of $1.99 billion was flat year over year (YOY) and 245 basis points (bps) below MarketBeat’s reported consensus, offering investors no catalyst.
Internally, three of the four segments grew sequentially and YOY, while communications declined. The computing and automotive and industrial segments rose to 48% of net revenue, up 1,100 basis points YOY. This shift is significant, as it reflects a structural pivot toward AI, a higher-margin business.
Margin news was equally mixed, as top-line weakness carried through to the bottom line. Gross margin improved by 400 bps, while operating margin increased by 330 bps. Net income grew by 50% on flat revenue, driving GAAP earnings per share (EPS) to 76 cents, a 49% YOY gain.
Guidance was a mixed bag, with legacy issues offsetting important strengths. Near-term headwinds include revenue and earnings forecasts that were narrowed and fell below consensus, but the market may already have priced in the impact. Despite the weak guidance, the stock price responded favorably, suggesting AMKR’s pullback may have bottomed.
Amkor’s balance sheet reveals the cost of its expansion plans, with debt doubling. However, this is not as much of a red flag as it is for some AI companies. Long-term debt is less than 0.5x equity, while cash, current and total assets, and equity have all increased. Leverage remains low. The likely outcome is that Amkor executes its expansions with relative ease, converts the investments into cash flow, and reduces debt.
Amkor's Pullback Creates Potential Upside
Analyst trends contributed to a stock price correction for AMKR in Q3, but the market may have overreacted, pushing the share price below the low end of analysts’ price target range. While near-term analyst trends remain a headwind, the stock trades at a deep value and could rise more than 50% to reach the consensus target.
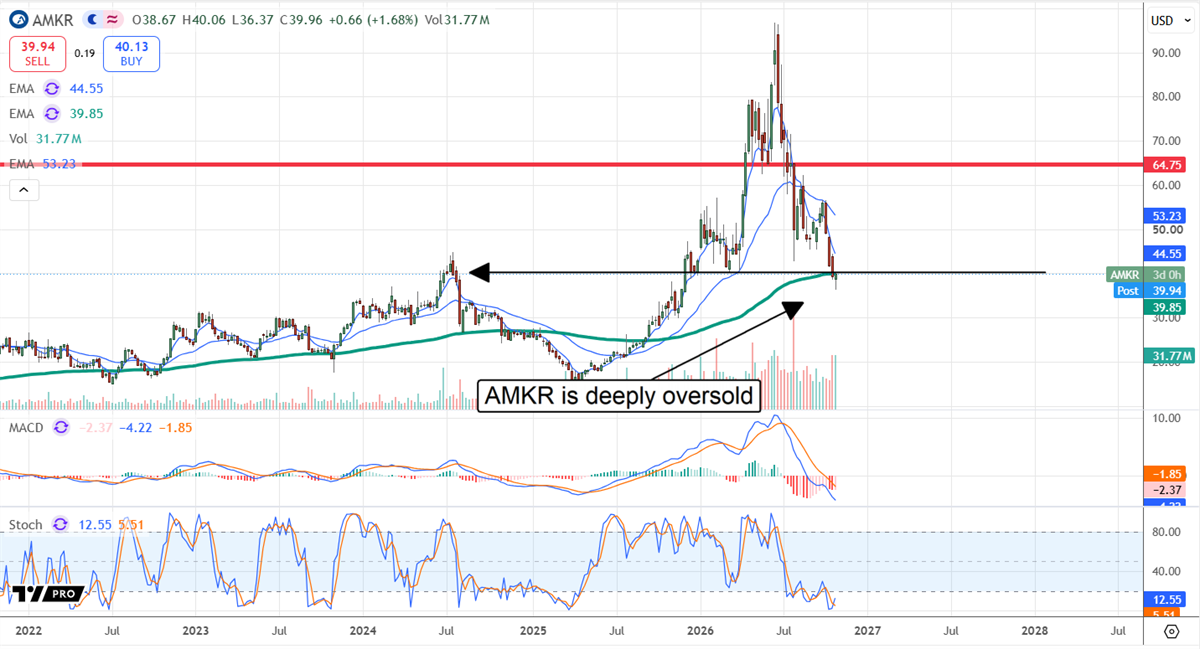
Price action reflects an oversold, overextended market that could rebound on a headline. The stock is at long-term lows, below a strong support target and the 150-day exponential moving average, and momentum is waning. Indicators such as MACD and stochastic are near the bottom of their ranges, while the MACD histogram indicates a divergence from the lows.
Divergence is a critical indicator that highlights a shifting dynamic. In this case, it suggests the bears are losing control and the bulls are regaining it. It does not guarantee a market reversal, but it indicates a rebound may be near. AMKR may continue to bottom in Q4, potentially rebounding as high as $50 before encountering resistance. The question is when AMKR will complete a reversal, which is unlikely to happen until sometime in 2027, when top-line growth resumes.
Amkor’s risks include customer concentration. Its top 10 clients account for the bulk of revenue—about 66% as of Q3—but this figure is improving. Q3 data show a 600-basis-point improvement in customer mix, driven by expansion. That expansion includes facilities across the company’s global footprint and investments in advanced packaging, effectively turning what the market perceives as a risk into a business tailwind.
. |


No comments:
Post a Comment