 A Message From Investors Alley Hi, Tim Plaehn here. Gold prices are breaking records. But while everyone else is fixated on headlines… They're missing something much bigger: There's a new way to collect income from gold. Not mining stocks.
Not options.
Not a single ounce of physical metal. Instead, it's a $15 fund that's quietly paying out up to $1,152 a month to regular investors… All thanks to a breakthrough strategy that transforms gold's rally into reliable monthly payouts. Click here to discover the gold income breakthrough most investors are missing. But move fast: the next payout is just days away. To your income,
Tim Plaehn
Chief Income Strategist, Investors Alley
Special Report
Lockheed's Stock Hasn't Priced In Its Own Backlog—Boeing's Might Already HaveAuthor: Ryan Hasson. Published: 9/23/2026. 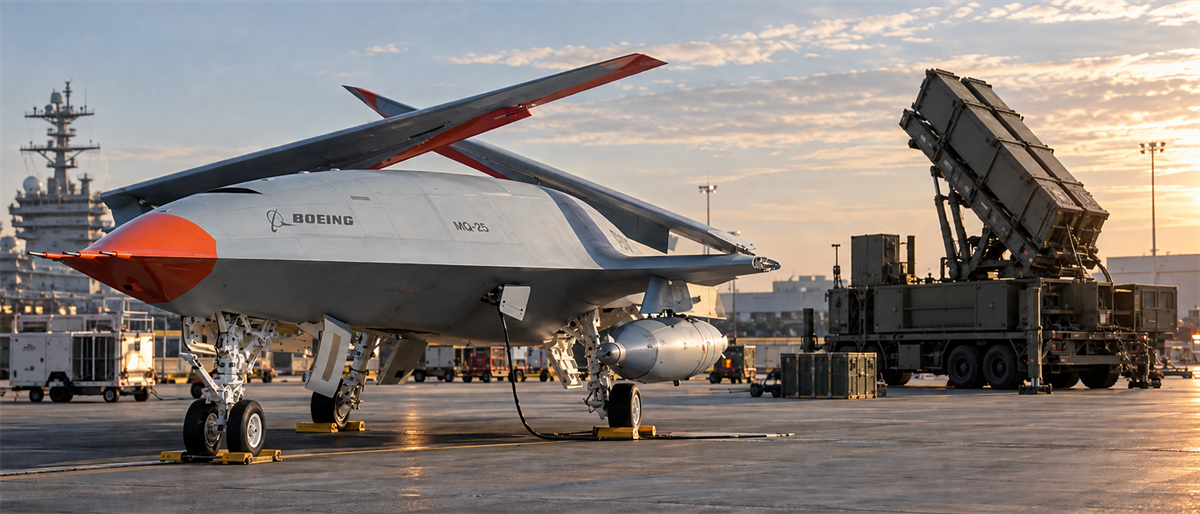
Key Points
- Boeing and Lockheed Martin secured nearly $1.9 billion in defense awards on Sept. 14, yet neither stock saw a major immediate reaction.
- Boeing’s valuation already reflects substantial turnaround expectations, while Lockheed Martin trades at a much lower multiple despite a growing backlog.
- For both companies, new contracts strengthen future revenue visibility, but margins, cash flow and execution remain the bigger questions for investors.
- Special Report: Porter flew 3,300 miles to investigate this system
The Pentagon opened its checkbook on Sept. 14, and two of America's largest defense contractors were on the receiving end. Boeing (NYSE: BA) landed a $562 million Navy contract to move its MQ-25A Stingray refueling drone into low-rate initial production—its most significant milestone yet for a program long plagued by delays. Lockheed Martin (NYSE: LMT) secured more than $1.3 billion across three separate awards, anchored by a $1.21 billion contract for the Precision Strike Missile Increment 2. Yet in both cases, the market barely blinked. That shared shrug is where the story gets interesting: The two stocks are being ignored for very different reasons. Boeing: The Good News May Already Be in the PriceBoeing's muted response reflects a stock whose valuation already bakes in a great deal of optimism, despite its sluggish returns this year. The market has spent the past couple of years betting on Boeing's turnaround under CEO Kelly Ortberg, and that faith is fully visible in the numbers. The stock trades at a striking 85 times trailing earnings, despite net margins of just 2.4%, while its balance sheet still carries an enormous debt load from its troubled recent history. This is not a cheap stock pricing in bad news. It is an expensive one, pricing in a recovery that hasn't fully shown up in the financials yet.
That helps explain why another Pentagon win did little. When a stock already reflects lofty expectations, incremental good news struggles to move the needle. The optimism isn't baseless, though: Boeing's backlog keeps growing, its commercial production is recovering, and analysts still see real upside. The stock has a Moderate Buy consensus and an average price target of $270.95, implying nearly 37% upside from the recent close near $198. But that target assumes the turnaround continues to translate into earnings. At 85 times profit, Boeing has to deliver, not just win contracts. Lockheed: A Laggard the Market Won't Re-Rate...YetLockheed's flat reaction stems from the opposite problem. Far from being priced for perfection, the stock has been left behind. Shares closed near $522, well below their highs from earlier this year and down roughly 24% from a 52-week peak of $692. Even as the company stacks up contract wins, the market has refused to reward it. The stock fell alongside other defense names in late September as reports of easing Middle East tensions deflated the wartime premium that had lifted the sector earlier in the year. The valuation could hardly be more different from Boeing's. Lockheed trades at around 17 times forward earnings, pays a 2.64% dividend backed by a strong payout history, and generates far healthier margins. Its consensus price target of $637.56 implies about 22% upside. On the surface, that looks like a clear disconnect from BA: a cash-generating defense leader, winning business at a rapid clip, and trading at a discount to both its history and its target. Why the Contracts Might Not Be EnoughDespite the steady flow of awards, analysts rate Lockheed only a Hold—a telling signal that the market wants more than order flow before it re-rates the stock. Contracts fill the backlog, but they don't automatically translate into the metrics investors are watching: margin expansion, free cash flow conversion, and clarity about the timing of future defense budgets. There are also legitimate reasons for the caution. Lockheed's projected earnings growth sits at a modest 8.5%, and the company has been burned in recent years by fixed-price development programs that chewed through cash. In other words, the market might not be questioning whether Lockheed can win work. Rather, it is questioning how efficiently that work converts into profit and cash. The Real QuestionSo, which stock could be the better potential opportunity? Boeing offers the larger implied upside to its target, but only if a richly valued turnaround delivers on lofty expectations. Lockheed offers a cheaper valuation, a real dividend, and a mountain of contract wins, yet sits under a Hold rating precisely because the market is holding out for proof beyond the backlog. Boeing's price may already reflect its good news, while Lockheed's may not yet reflect its own. But that gap will close only if Lockheed can turn its growing list of contracts into the margins and cash flow investors are quietly demanding.
All information contained herein is copyright 2025, Magnifi Communities LLC.
. |


No comments:
Post a Comment