 A Message From TradeSmith Dear Reader, You're probably hearing all kinds of wild rumours about the best way to play AI right now... The SpaceX IPO created 4,400 new millionaires... and OpenAI is reportedly planning its own $1 trillion IPO as early as this fall, which is expected to create even more overnight millionaires... While early holders of Nvidia have had the chance to make millions of dollars on just one stock. (One schoolteacher in New Hampshire retired early after making $2,545,000 on the stock.) MIT says right now is the best time in history to become wealthier, thanks to AI. But the truth is... The best way for ordinary folks to take advantage from what's happening isn't to speculate on AI IPOs... or try to guess which stock will be the "next Nvidia". It's simply to hold these five stocks. Put simply, our system (which is built on an AI platform pioneered by Google) ranks every stock in the S&P 500... And narrows everything down to just five names. There are no complex charts to read. No spending hours in front of a computer screen. No guesswork. All you do is buy five stocks, then hold them for a month. Our backtests show this simple approach could make you 1,000% on your money, without ever ‘holding and hoping' AI stocks themselves. And it could grow your money much faster than the market. For instance, in August you'd have made 4x more money holding just our Top Five Stocks, compared to the S&P 500. That's why I'm trying to share my free demo with as many folks as possible, while there's still time to try this out for yourself. Everything you need to know is here. Regards, Keith Kaplan
CEO, TradeSmith P.S. Sam Altman says AI will be "as essential as electricity" in the future. That's a very grand claim. But it doesn't tell you where your money should be for the best chance to profit and avoid falling behind. That's why I'm urging you to try our new AI tool now and potentially grow your money 10x using just five stocks. Get the full details here.
This Month's Bonus Article
Jabil’s Double-Beat and Raise Is a Signal That This Rally Will ContinueSubmitted by Thomas Hughes. Date Posted: 10/1/2026. 
Key Points
- Jabil reported a double-beat quarter with revenue up nearly 29% year over year and adjusted earnings per share rising almost 34% to $4.40, driven largely by AI demand.
- Analysts maintain a bullish Buy consensus with about 90% Buy-side bias, and shares trade well below the lowest price target, suggesting further upside potential.
- Jabil continues aggressive share repurchases and forecasts free cash flow growth, while institutions, which own more than 90% of shares, have been buying heavily.
- Special Report: “Elon’s nightmare” could fund your retirement
Whether the market response was tepid or not, Jabil’s (NYSE: JBL) recent double-beat earnings report was a buy signal. The results reinforced the thesis that has driven the shares higher and strengthened the company’s forward outlook. AI is driving a surge in demand across the company's product lines, pointing to a sustained upcycle and strong cash-generating capacity.
Cash-generating capacity is the core thesis, as Jabil is the muscle behind prominent names such as Apple (NASDAQ: AAPL), Cisco Systems (NASDAQ: CSCO), and Johnson & Johnson (NYSE: JNJ), helping turn demand for their products into reality. Jabil’s dividend is a token, yielding less than 0.25%, intended mainly to keep dividend-focused funds and institutions in the mix. The firm aggressively repurchases shares and appears capable of continuing to do so next year. Highlights from its last fiscal year included about $1 billion in repurchases, up year over year and sufficient to reduce the share count by 3.6%, along with a free cash flow payout ratio of about 69%. Looking ahead, management forecasts free cash flow growth in the coming year, signaling the capacity for accelerated buybacks and greater shareholder leverage. That outlook may provide an incentive to buy shares at current levels. Jabil Boosted by AI, Shows Strength in All CategoriesJabil posted a solid quarter, with revenue growth accelerating sequentially and year over year (YOY) to nearly 29%, its fastest pace in more than five years. Revenue growth also outpaced consensus by a wide margin—approximately 900 basis points (bps)—driven by 56% growth in Intelligent Infrastructure. Intelligent Infrastructure did the heavy lifting, but it was not the only segment to show strength: Regulated Industries grew 9%, while Connected Living/Digital Commerce was flat. CEO Mike Dastoor also highlighted several end markets unrelated to data centers and AI infrastructure, including automotive, healthcare, energy, defense, aerospace, and warehouse automation. Margin news was another bright spot. The company faced cost pressures and gross-margin headwinds, but both were less severe than expected and were offset by operational improvements. Selling, general, and administrative expenses increased at a much slower pace than revenue, showing that Jabil is becoming more efficient as it grows. That helped earnings rise faster than revenue. Adjusted earnings per share rose nearly 34% YOY to $4.40, outpacing top-line growth by about 500 bps, with this strength expected to carry into the coming year. Guidance is a key reason the stock’s uptrend could continue. Jabil’s guidance for the next quarter and full year is strong across the board, with revenue and earnings expected to be well above MarketBeat’s reported consensus. The likely outcome is that JBL continues to build momentum, operating at the high end of its expected range, if not exceeding it, and lifting its year-end outlook along the way. Analysts’ Caution Triggers Buying Opportunity in Jabil SharesAnalysts were generally bullish following Jabil’s release, highlighting the revenue strength and earnings quality. However, they also took a cautious stance, focusing on back-end margin expansion and the upfront cost of the company’s capacity buildout. No analysts revised a price target or altered their sentiment immediately following the report, leaving the trend unchanged. The trend includes steady coverage, a Buy consensus with a 90% Buy-side bias, and a forecast for nearly 50% upside from Q3’s support levels to a fresh all-time high. More importantly, JBL trades well below the lowest analyst price target, signaling a deep-value opportunity and the potential for explosive upside as stronger catalysts emerge. Institutions are likewise bullish on Jabil's stock, citing its cash flow, capital returns, and underlying demand for its clients' products. They own more than 90% of the shares, have bought aggressively over the trailing 12 months, and ramped up activity in Q3 to a record level. 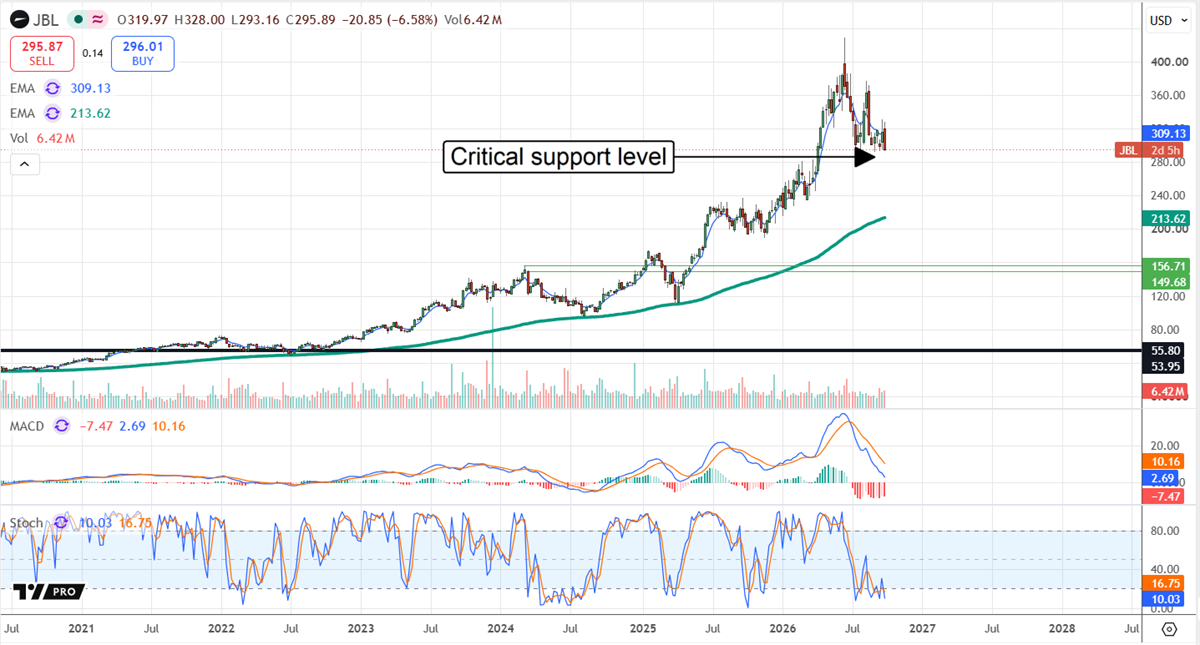
JBL’s price action reflects a bullish market posture. The stock is up more than 35% YOY and more than 100% over the past two years, while the 2026 pullback has offered value relative to recent peaks. A deeper pullback is possible, but strong support is evident as September comes to a close, limiting the downside risk. The likely scenario is that JBL remains near this level until more news becomes available, likely in upcoming earnings reports. The market may not be getting JBL’s report wrong so much as the price action reflects the split between short-term traders and long-term investors. Short-term traders focus on near-term bottlenecks, AI fears, and capacity costs, potentially failing to price in the impact on long-term cash flow. Long-term investors, focused on cash flow, capital returns, and capital gains, can look past upfront costs and focus on the demand curve, which is improving quarterly across numerous end markets—not just AI. Jabil’s biggest risk now is execution. Investors need the company's strategy to progress without hiccups, which could prove challenging given the advanced nature of AI hardware and industry-wide bottlenecks.
This ad is sent on behalf of TradeSmith at 1125 N. Charles Street, Baltimore, Maryland 21201. If you’re not interested in this opportunity, please click here.
This ad is sent on behalf of TradeSmith at 1125 N. Charles Street, Baltimore, Maryland 21201. If you’re not interested in this opportunity, please click here.
. |


No comments:
Post a Comment