 A Message From Paradigm Press Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader, Jeff Bezos is terrified. He will be down on his knees, hands out, begging Elon for mercy. Because Elon is about to do something that will: Cut Amazon out of the AI race ENTIRELY… Completely DESTROY Blue Origin… And take control of the potential $25 TRILLION DOLLAR PER YEAR AI INDUSTRY And in his wake, potentially create 1,806,000 NEW millionaires over the coming years… Starting September 25. And this is your chance to be one of them. Elon Musk is currently quietly planning the biggest project of his entire career. And a single FCC filing proves it, click here to see why. This is bigger than Tesla, SpaceX, and X combined. And I believe it will not only cement Elon as the winner of the AI race… It will allow Elon to control the entire industry. Something of this magnitude has never happened in the history of the human race. And it’s happening FAST. According to my timeline, you must act by September 25. I explain everything right here. >>>This is your free Millionaire Maker Masterclass… and it starts right now. Sincerely, James Altucher P.S. I am giving away a gift worth $1,000 to the first 1,000 people who watch and take action on my Masterclass offer today. No purchase necessary. ZERO credit card required. Just click here to watch my free video, and I’ll show you how to claim yours.
Saturday's Bonus Content
Micron’s AI Memory Boom Could Send Shares 100% HigherSubmitted by Thomas Hughes. Published: 9/16/2026. 
Key Points
- Analyst consensus rates Micron stock a Buy with 92% bullish bias, forecasting upside toward $1,295 and potentially $2,000 per share.
- Micron's chart technicals point to a $1,600 to $2,400 price target range, supported by a strong rally and MACD convergence signals.
- Persistent high-bandwidth memory demand, sold-out capacity through 2027, and over $100 billion in orders suggest tightness will continue for years.
- Special Report: The #1 stock to own BEFORE December 8th
Signals ranging from price action to analyst sentiment point to another massive run for Micron (NASDAQ: MU) stock. While headwinds and hurdles—including market angst, profit-taking, and repositioning—are weighing on price action today, long-term trends suggest at least another 100% upside. The hurdle in September is the broad call to slow AI’s advancement. Micron Is Well-Positioned for AI’s Virtuous CycleThe news reads as a red flag, but it’s also a red herring: Alarm over runaway models obscures who actually stands to gain if AI’s advance stalls.
As concerning as the advancement of uncontrollable models may be, they aren’t what AI companies are worried about. In this scenario, slowing AI’s advancement—cough, cough, pausing training of the most expensive models—is what the market needs. It would reduce AI’s high upfront costs, enable hyperscalers to monetize the infrastructure already in place, improve cash flow, and reassure investors while affirming their ability to continue spending. Regarding regulation, as MarketBeat writer Chris Markoch likes to put it, what more could AI companies ask for than the government installing roadblocks for startups and widening their moat? For Micron, this means continued, persistent demand for its high-bandwidth memory (HBM) products. The biggest risk is an anticipated earnings cliff tied to capacity expansion and price normalization. Memory chip stocks command premium pricing in 2026, which is a central factor in Micron’s results and earnings outlook. The market is getting this wrong: This isn’t a legacy-style memory cycle in which demand spikes, peaks, and retreats, undermining pricing power. Instead, it’s the early stage of a long-running trend in which data-center demand and inference keep prices elevated. The concern is that efficiency gains will reduce the amount of memory each query requires. But efficiency isn’t the memory killer. Rather, it makes inference more affordable, and affordability drives demand, increasing the number of queries and the need for memory. Micron Winds Up for Big Move, Technicals Point to $1,600-$2,400 RangeMicron’s chart price action is very bullish. The market has rallied strongly over the trailing 12 months, rising almost $800, or 500%, and has also crossed an inflection point, creating a price gap that was later confirmed as support. The weekly chart shows a robust rally and consolidation range, likely signaling continuation. The critical details are the magnitudes of the range and rally, which approach $400 and $800, respectively. These are the projections for future price action, assuming a fresh high is set, putting the technical price targets at $1,600 and $2,400. Among the more bullish technical factors is the MACD convergence. MACD convergence signals a strengthening market that is likely to retest existing highs and move on to new ones. The technical risk is that the price will top out near existing highs, but earnings and analyst trends suggest otherwise. 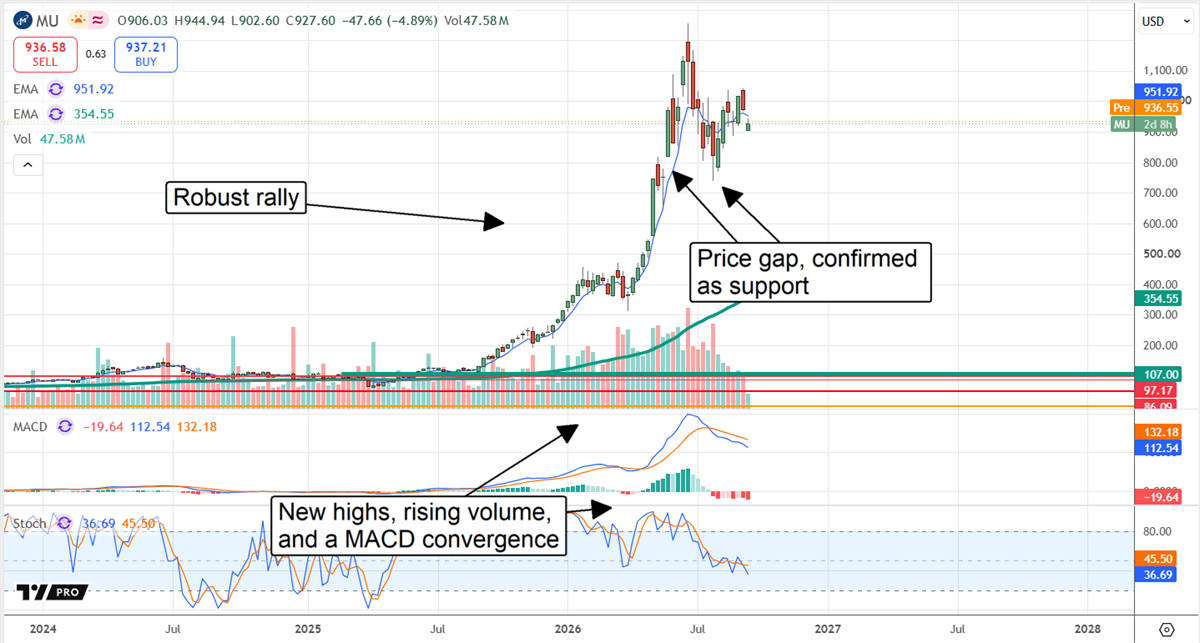
Micron’s analyst trends are as bullish as they have been over the last two years. MarketBeat’s data reveals steady, firm coverage, with 38 analysts showing strong conviction. They rate MU a consensus Buy, with a 92% Buy-side bias, and the price target trend is upward. The consensus forecasts a move to $1,295, representing 40% upside as of mid-September and enough to set a fresh high. More importantly, the trend points to a consensus-or-better price point, with the high end at $2,000—more than 100% upside and within the technical targets. Capacity Constraints to Continue: HBM Prices Aren’t Going to Fall SoonThe catalyst for MU stock is capacity constraints. The market focuses on expansion plans but fails to understand that capacity increases aren’t expected to significantly impact supply until at least late next year. Market tightness is likely to linger through 2028 or longer. More aggressive forecasts suggest that tightness will persist into 2031, and there are numerous reasons to believe them. Not only is the DRAM market neglecting its legacy business and creating shortfalls in non-AI markets, but system-wide HBM demand will continue to increase. Advanced Micro Devices (NASDAQ: AMD) isn’t using MU for its MI-450s but does use HBM—more than NVIDIA (NASDAQ: NVDA), in fact—and its sales are expected to explode over the next few quarters, keeping HBM supplies tight. If investors need further proof, they need only look at Micron’s backlog and commitments. As it stands, the company has more than $100 billion in logged orders, capacity is sold out through 2027, and it will likely sell out through the end of 2028 soon. Commitments include 16 major long-term supply contracts with set pricing, providing visibility. In the words of CEO Sanjay Mehrotra, demand exceeds capacity by approximately 50%. In this environment, there is no reason to think the HBM market will crash anytime soon. Acceleration is more likely. . |


No comments:
Post a Comment