 A Message From Paradigm Press Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader, Jeff Bezos is terrified. He will be down on his knees, hands out, begging Elon for mercy. Because Elon is about to do something that will: Cut Amazon out of the AI race ENTIRELY… Completely DESTROY Blue Origin… And take control of the potential $25 TRILLION DOLLAR PER YEAR AI INDUSTRY And in his wake, potentially create 1,806,000 NEW millionaires over the coming years… Starting December 8th. And this is your chance to be one of them. Elon Musk is currently quietly planning the biggest project of his entire career. And a single FCC filing proves it, click here to see why. This is bigger than Tesla, SpaceX, and X combined. And I believe it will not only cement Elon as the winner of the AI race… It will allow Elon to control the entire industry. Something of this magnitude has never happened in the history of the human race. And it’s happening FAST. According to my timeline, you must act by December 8th. I explain everything right here. >>>This is your free Millionaire Maker Masterclass… and it starts right now. Sincerely, James Altucher P.S. I am giving away a gift worth $1,000 to the first 1,000 people who watch and take action on my Masterclass offer today. No purchase necessary. ZERO credit card required. Just click here to watch my free video, and I’ll show you how to claim yours.
Just For You
Delta Air Lines Faces a Fuel Crisis—But There's a Silver LiningBy Thomas Hughes. Article Posted: 10/10/2026. 
Key Points
- Delta Air Lines shares could fall to around $70 in the near term due to rising fuel costs, though a rapid recovery is expected afterward.
- The company posted record Q3 revenue with GAAP revenue up 21% year-over-year, but margin compression from higher fuel costs caused flat EBIT and operating income.
- Despite several analysts trimming price targets after the report, the consensus rating remains Buy with roughly 20% upside and strong institutional ownership.
- Special Report: Elon Musk: “This will be Bigger than the Iphone”
Delta Air Lines (NYSE: DAL) is set up for a Q4 pullback as rising fuel costs cut into its earnings. The pullback could reach as low as $70 before the stock bottoms, but once it does, the recovery could be rapid. That’s because results remain robust, even with the pressure from higher fuel costs. The company produced record Q3 revenue, underpinned by broad-based demand, pointing to a strong Q4 and a high probability that the trend will continue into next year.
Within this outlook, oil prices are the wild card. They could remain elevated indefinitely, but they also face the risk of a rapid decline. The Iran conflict is weighing on oil prices today, but that impact is not expected to last much longer. Backwardation indicators suggest oil could fall back into the $80 range over the coming months, or potentially lower, if strong catalysts emerge. Shifts in the global oil market, improving Western production and alternative fuels, such as natural gas, are setting the stage for a possible oil glut in 2027. The takeaway for investors is that Delta’s earnings miss was self-inflicted: The company is absorbing higher fuel costs to sustain and grow market share. However, earnings remain sufficient to support strategic improvements while funding its dividend. 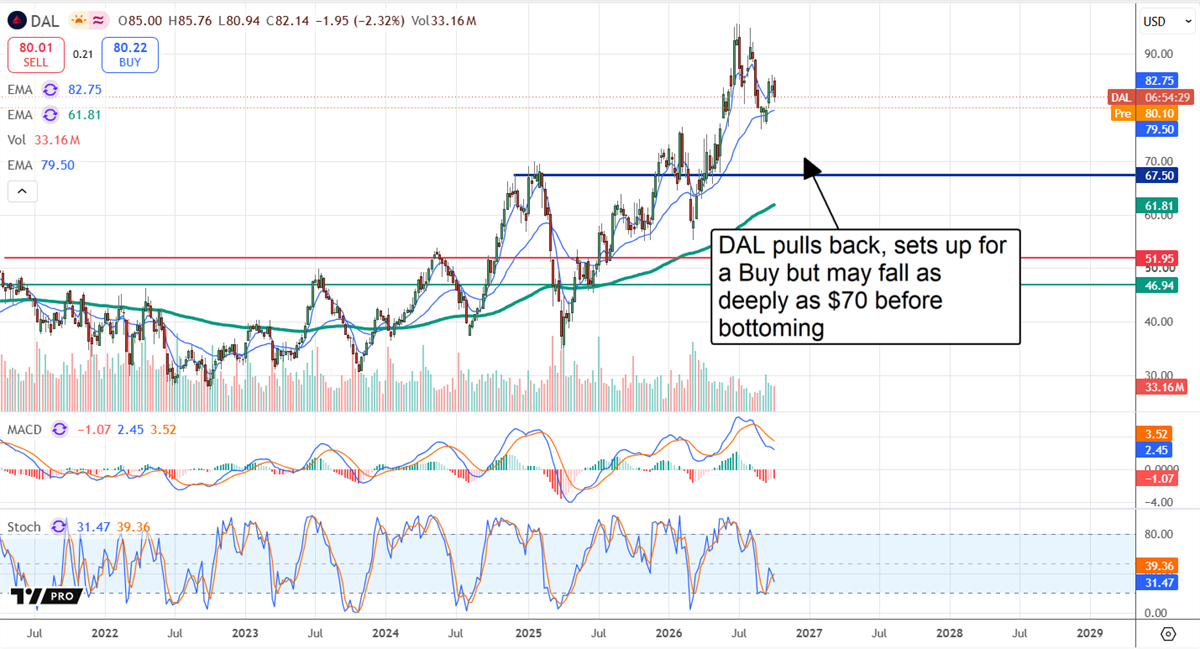
Delta Air Lines' Mixed Results Overshadow Record QuarterDelta Air Lines had a robust Q3, with GAAP revenue growing 21% year over year (YOY) to more than $20 billion. Adjusted revenue increased 16% to $17.6 billion, slightly missing consensus estimates. Broad-based demand and double-digit growth across regions drove the strength. Domestic revenue rose 16%, while international revenue increased 12% YOY. Among the international operations, Latin America was strongest, up 22%, followed by 13% growth in the trans-Pacific market and 11% growth in the trans-Atlantic market. Other signs of strength included the passenger mix. Premium revenue increased 18%, loyalty revenue rose 18%, and corporate revenue grew by double digits. These gains were complemented by a 29% increase in cargo revenue and strength in the maintenance division. Margin news is not as bad as it sounds, although margins did compress significantly. Key details include flat EBIT and operating income despite the 21% increase in revenue. The important caveat is that margin compression was driven by higher fuel costs, not operational failures. Flat results are still supportive of cash flow, free cash flow and balance-sheet health. Free cash flow totaled $1.9 billion year to date, enough to keep the company on track to reduce debt by $2 billion annually while paying its dividend. Debt reduction and dividends are central to Delta’s stock price outlook. Debt grew and the dividend shrank because of the COVID-19 pandemic, but both have since recovered. The narrative today is that Delta has regained investment-grade debt ratings, is strengthening its position and is trending toward more aggressive dividend increases. Although reinstated, the payout remains a fraction of what it once was despite the company’s significant growth. The likely outcome is that DAL sustains annual increases and potentially accelerates them over time as debt falls and free cash flow improves. Until then, the payment appears reliably safe, with a payout ratio below 15% of the earnings forecast. Analysts Trim Targets, Limiting Upside in Q4Analysts weren't happy with the report, focusing on margin contraction while overlooking market-share strength. The net reaction was a wave of price-target reductions, but investors shouldn’t read too much into them: The new targets remain aligned with the consensus, which forecasts approximately 20% upside. The bad news is that the reductions are likely to undercut market activity and keep the stock under pressure in the near term. However, the consensus view among 25 analysts remains Buy, with a 92% Buy-side bias in the data. Analysts are cautious but still reflect a bullish position, as evidenced by institutional trends. Institutions own nearly 70% of DAL stock and have been net buyers every quarter this year. The market gets it wrong by treating Delta as a run-of-the-mill airline with low margins and significant exposure to oil prices. Delta is a resilient consumer brand that ranks first in numerous surveys and drives revenue through seat miles while enhancing its margins through diversified revenue streams. Premium services, add-ons and loyalty drive revenue and keep consumers coming back. In addition, Delta’s unique position as the only airline with its own refinery helps alleviate some of the pressure from higher fuel costs. In this scenario, fuel-price spikes hurt the industry but enable Delta to gain market share and position itself for accelerated margin recovery as oil prices decline. Delta’s biggest risk is that oil prices remain elevated indefinitely or reach fresh highs, keeping margins under pressure throughout 2027. In that scenario, DAL's share price may remain under pressure through year-end or until relief in the oil market becomes a reality. . |


No comments:
Post a Comment