 A Message From Banyan Hill Publishing Dear Reader, Three days into his second term, President Trump signed Executive Order 14178. The press barely noticed. But buried inside was the legal green light for the boldest change to American money in over 100 years. And it’s finally about to take effect. I’ve spent months digging into what this order actually means.
What I found could send shockwaves through the financial system: Musk — with the quiet cooperation of the U.S. Treasury — is now positioned to “reboot” the dollar itself. Not someday. Potentially as soon as January 18. And it could all come down to one vote — led by Trump’s own Treasury Secretary. When it happens, life as we know it could change… and investors who saw it coming could make a fortune. Go here for the full story. Regards, 
Ian King
Chief Strategist, Strategic Fortunes
Exclusive Story
PepsiCo Stock Looks Poised to Bottom With High Yield, Deep ValueAuthor: Thomas Hughes. First Published: 10/8/2026. 
Key Points
- PepsiCo stock trades at a historically low valuation of about 15 times forward earnings with an approximately 4.7% dividend yield, offering value for long-term investors.
- Third-quarter results showed revenue up 5.6% year over year, driven by international strength, even as North America remained weak and guidance was trimmed.
- Institutional buying, oversold technical indicators, and ongoing turnaround efforts, including a North American portfolio reset, suggest PepsiCo's share price may be bottoming.
- Special Report: Nvidia pours 7 billion into a light speed AI breakthrough
PepsiCo (NASDAQ: PEP) faces some hurdles, but it’s doing what long-term investors need: generating cash flow and returning capital to investors. The opportunity in 2026 is an historically low valuation and share price, compounded by an historically high yield. While high bond yields have played a role in PepsiCo's stock price decline, investors should remember that bond yields won’t stay high forever—and PEP won't remain undervalued.
The same money invested in 10-year bonds will yield a little more than 5% over time, but that’s it. PepsiCo’s stock price will increase over the next decade while it continues to pay its dividend. In this scenario, investors buying PEP in Q4 2026 can lock in an approximately 4.7% yield and an outlook for significant capital appreciation. At about 15 times forward earnings, PEP stock trades at a 40% discount to historical norms, is deeply oversold, and is positioned for a long-term price recovery. Recovering its premium alone would put the stock near its existing highs; combined with the growth outlook, that recovery could carry it to fresh highs. PepsiCo’s Diversified Business and Strategic Shifts Drive GrowthPepsiCo had a decent Q3, with revenue up 5.6% year over year (YOY) and above consensus estimates. Growth was underpinned by a 3.1% organic increase driven by volume and pricing. Acquisitions added another 1.7%, while the remainder came from a foreign exchange-related tailwind. Regionally, North America was the weakest market, with PepsiCo Foods flat and Beverages up 5%. International was the bright spot, with International Beverages up 8% and EMEA, Latin America, and Asia-Pacific Foods all growing by at least that much. Margin news was mixed but sufficient to keep buy-and-hold investors interested, given the low share price. Reported margins expanded but were boosted by tariff refunds. On an underlying basis, core margins contracted, but less than expected, leaving adjusted earnings per share (EPS) up by about 2%. That EPS growth beat expectations by 5 cents, helping to offset the weak guidance. PepsiCo revised its guidance, firmed up its revenue target, and trimmed its earnings projections, which isn't typically good news. However, the market's response suggests investors expected worse, making further share-price declines less likely. Analysts and Institutions Limit PepsiCo’s Downside in Q4Analysts' responses to the release were muted, citing North American weakness and lower profit targets. As it stands, the 20 analysts tracked by MarketBeat are strongly aligned around a consensus Hold rating. The data indicate a bullish bias, and price targets highlight deep value. While consensus suggests 20% upside, PEP trades about 5% below even the lowest analyst price target. Institutional activity aligns with the thesis that PepsiCo’s stock price is bottoming. Institutions own a solid 73% of the stock and have accumulated shares for nine consecutive quarters. More importantly, buying activity ramped up in Q3 as the stock reached long-term lows and is likely to remain bullish because of the market disconnect. Retail traders are overreacting to the GLP-1 threat while ignoring the company's international strength, turnaround efforts, and strategic shifts to capture changing consumer habits. Capital Returns Help Put the Floor in PepsiCo’s Share PricePepsiCo's capital returns are attractive, including a high dividend yield and share buybacks. Share buybacks aren’t aggressive, but they reduce the share count incrementally each quarter. Highlights from Q3 include a slight YOY reduction in buybacks, but this was tied to the share price, which enabled the company to steadily reduce its share count at a lower cost. Looking ahead, PepsiCo is likely to continue reducing the share count at the same pace while increasing its dividend distribution. The company is a Dividend King and is unlikely to end its streak anytime soon. Chart price action is yet another indicator that PepsiCo’s stock price is at a floor. The stock broke through critical support ahead of the release but is rebounding with favorable indicators. The MACD reveals divergence from price, while the Stochastic indicator shows an extremely oversold market. 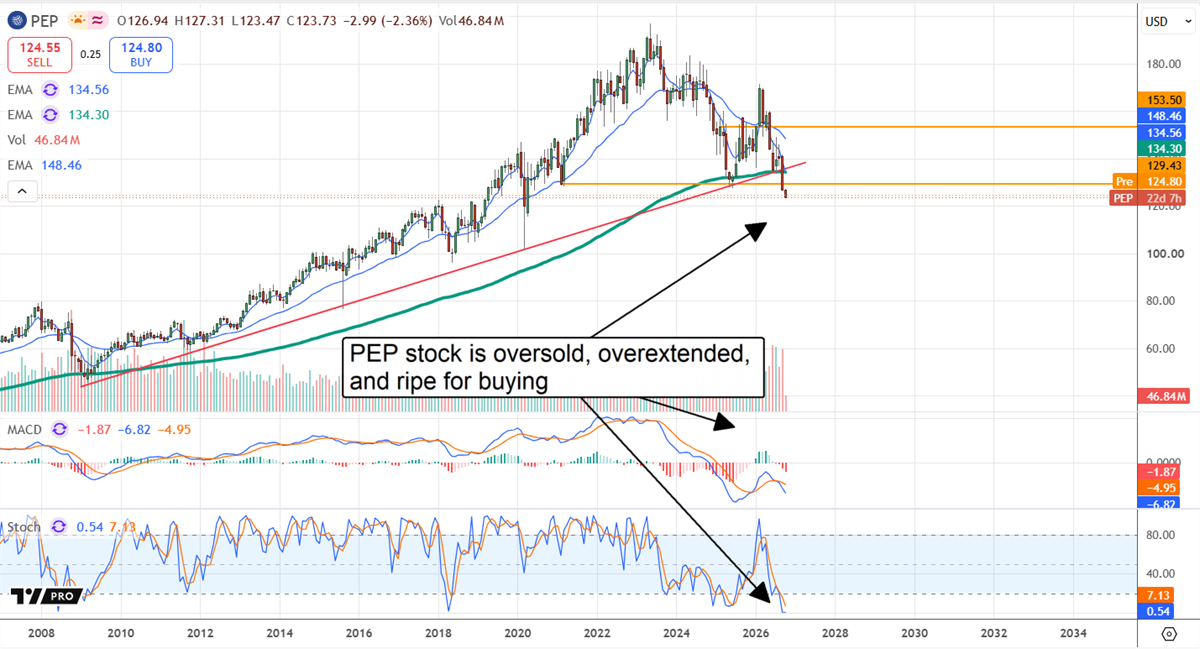
The only thing missing is a strong catalyst, and several are developing. Turnaround efforts include a massive North American portfolio reset, with a 20% stock-keeping-unit (SKU) reduction to streamline operations and improve shelf spacing, along with value pricing. These efforts are already showing traction, as demonstrated by the sequential improvement in Q3 compared with Q2. PepsiCo’s risks are primarily external, including changing consumer habits, regulatory hurdles, and legal headwinds. Consumer habits are affecting the North American business but have not yet triggered structural declines, and turnaround efforts are underway. Regulatory hurdles and legal pushback are bigger issues, with local and national agencies targeting soda companies as unhealthy, while recalls could hurt consumer awareness.
This ad is sent on behalf of Banyan Hill Publishing.
This ad is sent on behalf of Banyan Hill Publishing.
. |


No comments:
Post a Comment