 A Message From Stansberry Research Dear Reader, For years, I've recommended to my readers to put a big chunk of their retirement money into one stock: Berkshire Hathaway. And for anyone who followed my recommendation, they've had the chance to do very well. But now, I may have found an even better retirement stock for the years to come—and today I'm going to show you the name and stock symbol, totally free of charge. (Click here to get the specifics.) This is a company few have heard of, yet it's at the epicenter of America's two most important industries right now. (Yes, AI is one of them.) In my new presentation, I explain everything you need to know about this incredible company, and I reveal the stock market ticker symbol, totally free of charge. No credit card or email address or anything else required. It's incredible story of a company unlike any other in America. The returns could be massive (much bigger than Berkshire in recent years)... the dividends are massive, too... and the best part of all is that I think the next few years will be even more lucrative for this stock than the past, because the assets the company owns are critical for America's two most important industries right now. That's why I believe this might be the greatest retirement stock in America right now. Click here to get the name and ticker symbol of this amazing stock, totally free of charge. Again, no credit card, or email required. Regards, Whitney Tilson
Editor, Stansberry Research P.S. One more thing. This stock is so powerful, one famous money manager put 60% his entire multi-billionaire fund into the exact same stock I'm going to tell you about today. It sounds crazy until you see exactly what this company owns and does. You'll find everything you need to know, including the stock name and ticker symbol, here.
Today's Bonus Story
NVIDIA’s Record High Raises a Bigger Question About How Far the Rally Can RunAuthor: Thomas Hughes. Posted: 10/5/2026. 
Key Points
- NVIDIA broke out of a major trading range and reached a new all-time intraday high on Oct. 2.
- NVIDIA’s analyst targets and earnings outlook remain bullish as Vera Rubin ramps and AI infrastructure demand expands.
- NVIDIA’s growth continues to benefit semiconductor and memory partners, although supply constraints remain a key risk.
- Special Report: Do NOT Buy SpaceX – Do This Instead
NVIDIA’s (NASDAQ: NVDA) stock price did something interesting in early October, rising to a new all-time high. The move broke the stock out of a significant trading range, extended the uptrend and points to continued gains in the coming months and quarters. Technically, the move brings several target projections into play, suggesting the stock could rise by solid double digits in the near term and by a high triple-digit percentage over the long term. That could set the stage for this $5.7 trillion company to reach a $10 trillion valuation. Investors should consider that milestone within the next year or two, and it may be only a stepping stone toward what the company could ultimately be worth.
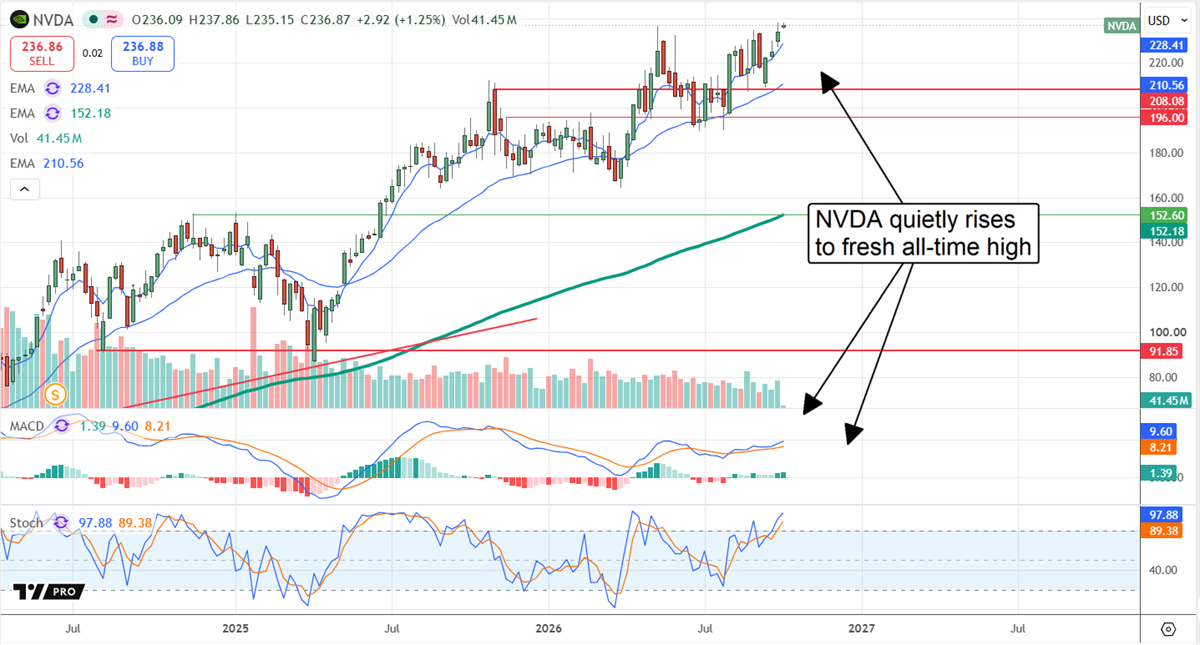
Technical targets are based on the magnitude of the existing range and the rally that preceded it. They amount to $40 and $65 moves that, when projected from the breakout point, target $275 and $300. The $275 to $300 range is coincidentally just below the analysts' consensus price target of $320.71, strengthening the case for NVIDIA’s modest near-term upside potential. Trends Matter: NVIDIA and AI Are Not a BubbleTrends matter for stock prices because the market tries to anticipate developments, and rising or falling targets influence investor expectations. In NVIDIA’s case, the trend is upward, with MarketBeat data showing rising coverage, firm sentiment, a bullish bias and price targets reaching as high as $515. That target implies more than 100% upside from the early October breakout point and is well above the technical targets. The latest coverage includes commentary from DBS Group’s chief investment officer, Hou Wey Fook. Fook pointed to Bloomberg-compiled data showing that NVIDIA trades at about 17 times 12-month forward earnings and questioned how AI can be a bubble at that multiple. NVIDIA normally trades in the 30x to 35x range, a premium once tied to its GPUs. Historical bubbles, including the dot-com bubble, saw valuations skyrocket into the triple digits before they burst. Looking further ahead, NVIDIA remains an execution story, and its 10-year outlook suggests the stock could be worth substantially more. Earnings estimates also point to continued rapid growth. The company is expected to grow earnings by approximately 70% over the next year, and the consensus could prove conservative. NVIDIA itself expects unit volumes to double, underpinned by the Vera Rubin release. That could unleash another wave of data center construction, since Oracle (NYSE: ORCL) and many hyperscale and neocloud backlogs are tied to next-generation technology. The takeaway for investors is that NVIDIA’s AI growth story remains intact. That is very bullish for its ecosystem partners, AI generally, the tech industry and the S&P 500 index. NVIDIA’s Ecosystem Partners: A Powerhouse Portfolio of Tech LeadershipThe number one beneficiary of NVIDIA’s ecosystem dominance is Taiwan Semiconductor Manufacturing Company (NYSE: TSM). The company is a key foundry and advanced packaging partner for NVIDIA’s GPUs, CPUs and interconnect technology. It benefits from volume, scale leverage and demand for higher-margin advanced packaging services, which add up to sustained double-digit revenue growth and accelerating profitability. Micron (NASDAQ: MU) and SK Hynix (NASDAQ: SKHY) are likewise well-positioned for NVIDIA’s growth surge. Together, they account for nearly 100% of the high-bandwidth memory (HBM) market, which is critical to AI at all levels. They benefit from exponentially growing demand, as each NVIDIA GPU relies on numerous stacks of HBM chips, as well as from supply constraints. Current forecasts suggest memory supply will remain tight through at least 2027, with Micron indicating that shortages could take considerable time to ease. The implications for the S&P 500 are equally robust, with tech strength expected throughout infrastructure, hardware and software systems. More importantly, rapidly expanding capacity is driving application development, which is creating demand for additional capacity in a virtuous cycle. Bottlenecks, including hardware, power and permitting, exist and threaten to slow AI’s progress, but they are incremental and may slow, rather than derail, the long-term outlook. In the long term, businesses, enterprises, agencies and sovereign governments need AI to unlock efficiency and advancement. The build-out will continue, and the companies monetizing it could see their stock prices rise. NVIDIA’s biggest risk is obsolescence, but it is working hard to keep that threat at bay. Investments in software, hardware and applications are paying off, cementing the company as the global base layer for AI. Catalysts include the upcoming Q3 earnings release, estimated for Nov. 18. Analysts expect 90% revenue and earnings growth, and investors are likely to be pleasantly surprised. Blackwell is in full production, with demand exceeding supply.
This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here.
This ad is sent on behalf of Stansberry Research, 1125 N Charles St, Baltimore, MD 21201. If you would like to optout from receiving offers from Stansberry Research please click here.
. |


No comments:
Post a Comment