 A Message From Altimetry Small Colorado Company (Backed by Sam Altman) Could Save U.S. Power Grid 
A small Colorado company now owns rights to a tech that could save the entire public power grid from collapse. And billionaire Sam Altman is now an investor. Click here to learn this company's name for free.
This Week's Exclusive News
The Case for Buying High-Yield General Mills Just StrengthenedBy Thomas Hughes. Article Published: 9/24/2026. 
Key Points
- General Mills' lackluster fiscal Q1 2027 results reflect the divestiture of its yogurt business, with an inflection point now approaching.
- The dividend remains covered by earnings and cash flow through FY2027 and FY2028, offering investors an approximate 6.9% yield at historically low share prices.
- Institutional investors have been accumulating shares near a technical bottom, even as analysts hold a cautious Reduce consensus rating on the stock.
- Special Report: Champion stock-picker warns, “Watch out for the Anthropic IPO”
General Mills (NYSE: GIS) is working on a turnaround and nearing an inflection point. Its Q1 results for fiscal 2027 (FY2027) were lackluster, but investors must remember that they were measured against tough comparisons and included the impact of a significant divestiture. General Mills sold its yogurt business to focus on core growth opportunities and operational efficiency, positioning itself to sustain long-term growth. The key point is that the inflection point is now here and reflected in the stock’s price.
Internal results reveal the impact of the divestiture and turnaround efforts. While North America Retail contracted by 7%—with 400 basis points of the decline attributable to yogurt—it was the only segment to show weakness. North America Pet was not strong, but flat results are better than a contraction and provide a more solid foundation on which to build. More importantly, areas of strength, such as North America Foodservice, are expanding. Companywide organic sales were flat, with only the yogurt business needing to be removed from the calculations for growth to return. As it stands, the company is optimistic, forecasting the potential for positive organic growth by year-end. General Mills Dividend Safe in FY2027, Safer in FY2028General Mills' dividend faces headwinds but appears reliable for FY2027. The payout ratio is rising, but forecast earnings and expected annual cash flow cover the dividend, with cash flow being the more important measure. The biggest risk to the dividend is stalled growth, but growth will likely return by the end of FY2028, mitigating that risk. In this scenario, the dividend-growth outlook is more of a tailwind than a headwind, providing a future catalyst to lift price action and accelerate the stock’s recovery. Until then, investors buying in late September can lock in an approximate 6.9% dividend yield at historically low prices, more than double the core inflation rate. Institutional holdings reflect confidence in General Mills' long-term value, and the group's activity aligns with a technical bottom in the stock price. Institutions own more than 75% of the stock and have been accumulating shares in 2026, ramping up activity into early Q3, according to MarketBeat data. Trading volume has steadily increased this year, reaching record levels as GIS shares hit historically low prices. 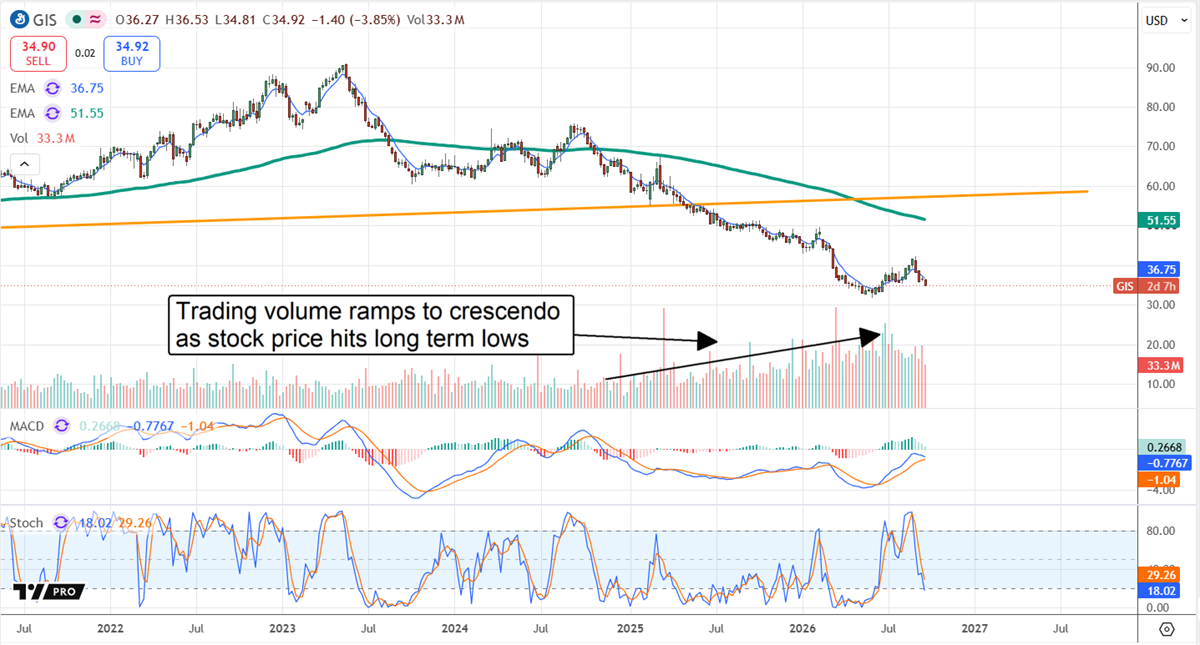
The Q3 spike in institutional activity also suggests that downside is limited in late Q3 and Q4. The likely outcome is that GIS shares trend sideways, if not higher, over the next two to three quarters while the market waits for systemwide growth to return. Analysts are a more pressing concern, with consensus pegged at Reduce. The caveat is that the bearish bias is minimal, at only 30%, and late August and early September activity aligns with a market bottom. The consensus includes reaffirmed bullish ratings and higher price targets, confirming the low-$30s as a price floor. General Mills Clears Hurdle, Reaffirms GuidanceGeneral Mills had a tough quarter, with sales in its core market contracting even on an adjusted basis. However, net revenue of $4.4 billion beat consensus by a slim margin, as did margins. GAAP margins contracted by a high-double-digit percentage, but that figure includes the impact of yogurt. Adjusted margins contracted by a low-single-digit percentage, leaving earnings down by a low-teens percentage versus last year. Key details include $397 million in net income and the expectation that full-year results will outpace expectations. Guidance was reaffirmed, with the company expecting flat to slightly negative organic sales and adjusted earnings per share of $3.10, 3 cents more than analysts had anticipated. Balance-sheet highlights raise some red flags, with cash, total assets and equity down from last year, but the risks are minimal. The company is using its balance sheet to help sustain the dividend until the business turnaround gains visible traction, but it has the capacity to do so. Mitigating factors include reduced liabilities and flat debt, which leave cash flow relatively unimpaired, though diminished. Another catalyst is brewing: share buybacks. General Mills paused buybacks to conserve cash but will likely resume them as cash flow improves. No buybacks were made in Q1 FY2027, but the average share count is down about 1%. This year’s risks include the impact of GLP-1s. GLP-1s are changing how Americans eat: People are snacking and eating less overall and are more focused on protein. To respond, General Mills is adapting to the industry by offering more protein-rich, nutrient-dense options. The company is also leaning into technology to improve efficiency, including returns on invested capital. Investors should monitor dividend coverage and the risk of dividend cuts, which could increase as the year progresses. The key question is whether the company can execute its expected pivot.
This ad is sent on behalf of Altimetry, 110 Cambridge Street, Cambridge, MA 02141. If you would like to optout from receiving offers from Altimetry please click here.
This ad is sent on behalf of Altimetry, 110 Cambridge Street, Cambridge, MA 02141. If you would like to optout from receiving offers from Altimetry please click here.
. |


No comments:
Post a Comment