
A Message From Weiss Ratings
Dear Reader,
I need to speak with you directly.
I want you to see the most important warning of my career …
And one of the most important warnings any American family will receive before the next great financial crisis hits this country.
I'm Dr. Martin D. Weiss. I'm a Wall Street Journal, BusinessWeek, and New York Times best-selling author.
And for 55 years I have run Weiss Ratings … the only 100% conflict-free, independent financial rating agency in America.
We are paid by no one we rate. We answer to no one but our subscribers.
And in the 55 years since I issued my first public warning before a financial crisis, I have publicly predicted six major American crashes, before they happened.
What I'm seeing now is a $3 trillion problem.
And the biggest danger right now is NOT just another stock market crash.
The biggest danger is NOT only a major bank failure.
Rather, it's a chain reaction of crashes and failures that could cause a global freeze in the financial markets. And it starts here:
Go here now to see the most important warning of my career
Good luck and God bless!
Sincerely,
Martin D. Weiss, PhD
Weiss Ratings Founder
This Week's Exclusive Story
D-Wave Quantum Has Long-Term Potential, But Is Now the Time to Buy?
Author: Thomas Hughes. Posted: 11/10/2026.
Key Points
- D-Wave Quantum shares are in a technical downtrend with weak volume, and fading enthusiasm for quantum computing stocks suggests further declines are likely.
- D-Wave's elevated short interest and bearish technical indicators suggest continued volatility, although a positive catalyst could trigger short covering.
- Q3 results showed minimal revenue against large losses and rising share dilution, raising concerns about cash burn despite roughly $503 million in liquidity.
- Special Report: That feeling in your stomach
D-Wave Quantum (NASDAQ: QBTS) may be a good long-term investment because of quantum computing’s potential. The technology could open new industries by enabling complex solutions faster than is currently possible, potentially revolutionizing sectors such as healthcare, energy and materials. However, these investments are long-term plays. The question in late 2026 is whether QBTS is a good buy now, and the answer is quite different. While the long-term opportunity is robust, fundamental factors and market action suggest the stock could move lower—potentially much lower—before finding a bottom.
The primary factor is the timeline to broader adoption. Some industry roadmaps target major advances within the next five to 10 years, potentially unleashing the industry. But such breakthroughs are not guaranteed for any specific company, including D-Wave Quantum.
Five to 10 years is a long time, even at the low end, and the range is wide, with no guarantees. This leads to a truth that would-be investors must face: quantum computing isn’t as cool as it was a year or so ago. Quantum stocks were on fire in 2024 and 2025, riding a wave of euphoria, optimism and hope that has since faded. Today’s quantum stock market conditions are generally unenthusiastic, and enthusiasm is what drives speculative stock prices higher.
The Technical Reality: QBTS Is in a Downtrend
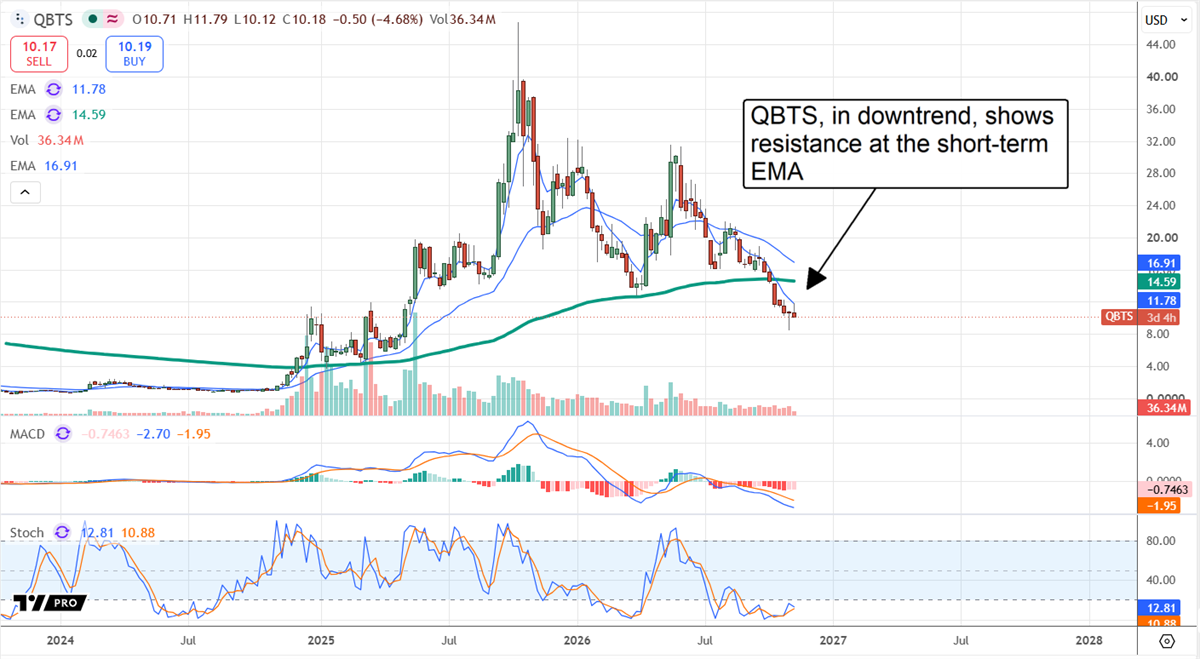
D-Wave’s price chart shows a downtrend in both daily and weekly trading. The share price is well below the longer-term exponential moving averages (EMAs), and the shorter-term EMAs have acted as resistance since the Q3 earnings release, suggesting the downtrend could continue. The stock could become oversold and rebound, but any rebound is unlikely to gain or sustain traction without a bullish catalyst. Other signs of weakness include dwindling, lackluster trading volume, reflecting a market that is losing interest in the story.
Risks include short interest, which is high and has risen in recent reports. It isn’t the highest among public companies, at 21.67% of the float as of Oct. 15, but it is high enough to contribute to volatility, particularly in the absence of a bullish catalyst. Potential catalysts will center on technological breakthroughs and their effects on revenue and earnings forecasts.
The upshot is that when a catalyst emerges, a short-covering rally could verge on a squeeze, given the five days to cover. At that level, it would take a week of average trading volume for short sellers to cover their collective position, suggesting at least a 5x spike in trading volume if a squeeze takes hold. That 5x figure is a minimum target: It will take more than news to trigger a squeeze; it will also require an influx of capital and a rapid decline in the number of available shares.
Analyst and Institutional Sentiment Isn’t Quite Strong Enough
Analyst and institutional data reflect confidence in the quantum thesis, but not high conviction across the board, and some sentiment has soured over the past year. MarketBeat tracks 16 analysts with current coverage, enough to provide some insight into the outlook, but trends are moving lower, including price target adjustments and rating changes. Consensus is pegged at Moderate Buy, with nearly 240% upside indicated. The risk is that price targets and ratings will continue to sour, giving buyers little incentive and creating a headwind for existing holders.
Institutions, meanwhile, have been net buyers as shares declined, but they own about 42% of the company, providing an uncertain support base. Bad news may not send them to the exits, but falling prices may not prompt them to buy, allowing the decline to continue.
Q3 results did not provide a catalyst for buyers or a reason for sentiment to improve. Revenue grew about 20% year over year and outpaced consensus, but amounted to just $4.5 million—far short of the company’s spending. Losses ranged from a $48.2 million net loss to a $53.5 million operating loss, or about 12 times revenue at the high end. The good news is that the company has substantial liquidity; the bad news is that cash burn has increased from the prior year and is expected to continue. Balance-sheet highlights include about $503 million in cash and marketable investments, plus up to $100 million in government funding contingent on certain milestones. The company’s runway will depend on future spending.
Dilution is another risk for investors to consider. QBTS’s weighted-average share count increased about 10% year over year in Q3 and more than 19% in the first nine months compared with the same period last year—a sizeable headwind that is unlikely to disappear. QBTS may not sell shares soon, but dilution will remain a constant threat until commercialization, which the existing runway is insufficient to reach. It may be only a matter of time before the company offers shares or raises debt.
. |


No comments:
Post a Comment