
A Message From Weiss Ratings
Dear Reader,
I need to speak with you directly.
I want you to see the most important warning of my career …
And one of the most important warnings any American family will receive before the next great financial crisis hits this country.
I'm Dr. Martin D. Weiss. I'm a Wall Street Journal, BusinessWeek, and New York Times best-selling author.
And for 55 years I have run Weiss Ratings … the only 100% conflict-free, independent financial rating agency in America.
We are paid by no one we rate. We answer to no one but our subscribers.
And in the 55 years since I issued my first public warning before a financial crisis, I have publicly predicted six major American crashes, before they happened.
What I'm seeing now is a $3 trillion problem.
And the biggest danger right now is NOT just another stock market crash.
The biggest danger is NOT only a major bank failure.
Rather, it's a chain reaction of crashes and failures that could cause a global freeze in the financial markets. And it starts here:
Go here now to see the most important warning of my career
Good luck and God bless!
Sincerely,
Martin D. Weiss, PhD
Weiss Ratings Founder
This Month's Featured Article
Lemonade's Revenue Soars 73%—So Why Did Its Stock Turn Sour After Earnings?
Authored by Thomas Hughes. Published: 11/8/2026.
Key Points
- Lemonade's third-quarter revenue grew 72.8%, driven by higher premiums and an expanding customer base.
- Management expects its first quarter of positive adjusted EBITDA in Q4 2026, although the company remains unprofitable on a GAAP basis.
- Lemonade shares fell sharply after earnings, despite improved guidance and a substantial short position that could contribute to future volatility.
- Special Report: I'm handing you this one free
Lemonade’s (NYSE: LMND)Q3 results reflect an accelerating growth story as the company approaches a major inflection point: the shift from a cash-burning start-up still reporting GAAP losses to one nearing profitability. With Lemonade forecasting its first positive adjusted EBITDA in Q4, the focus is now on execution, and execution is driving results that point to sustained growth and margin improvement.
The drivers are twofold: a growing customer base and deeper customer penetration, alongside improving efficiency. The result is significant operating leverage, which is expected to improve over time as in-force premium (IFP) growth outpaces the costs of acquiring customers. Operating leverage can support cash flow, which in the insurance industry could eventually fund capital returns—the endgame for investors.
Lemonade Outperforms in Q3: Offers Sweet Guidance for Q4
Lemonade had a strong quarter, with revenue growing 72.8% and outpacing the consensus estimate by about 4%, while gross earned premium (GEP) growth more than doubled. IFP growth came in at 34%, driven by 23% customer growth and a 9% increase in premium per customer. Annual dollar retention, a measure of premium retention, also improved by one percentage point to 86%.
The margin outlook is an equally important catalyst, alongside strong earnings and customer-acquisition trends. Lemonade has generated positive adjusted free cash flow for several quarters, extending the trend to six consecutive quarters in Q3, and is tracking toward profitability. Its GAAP loss was 56 cents per share, wider than the 51-cent loss a year ago but two cents narrower than analysts expected. The loss is expected to improve over the coming quarters as the company scales. The company’s AI platform helps it onboard large numbers of new customers without adding employee headcount.
Fourth-quarter guidance is the bullish catalyst, with Q4 results due in early 2027. Management not only guided for positive adjusted EBITDA for the first time in company history but also appears to have the capacity to meet its targets. Several trends support the outlook, including increases in customer count, penetration, IFP, and GEP, despite higher costs. Lemonade may follow through on its guidance, potentially exceed its own estimate, and trigger another bullish response in the market.
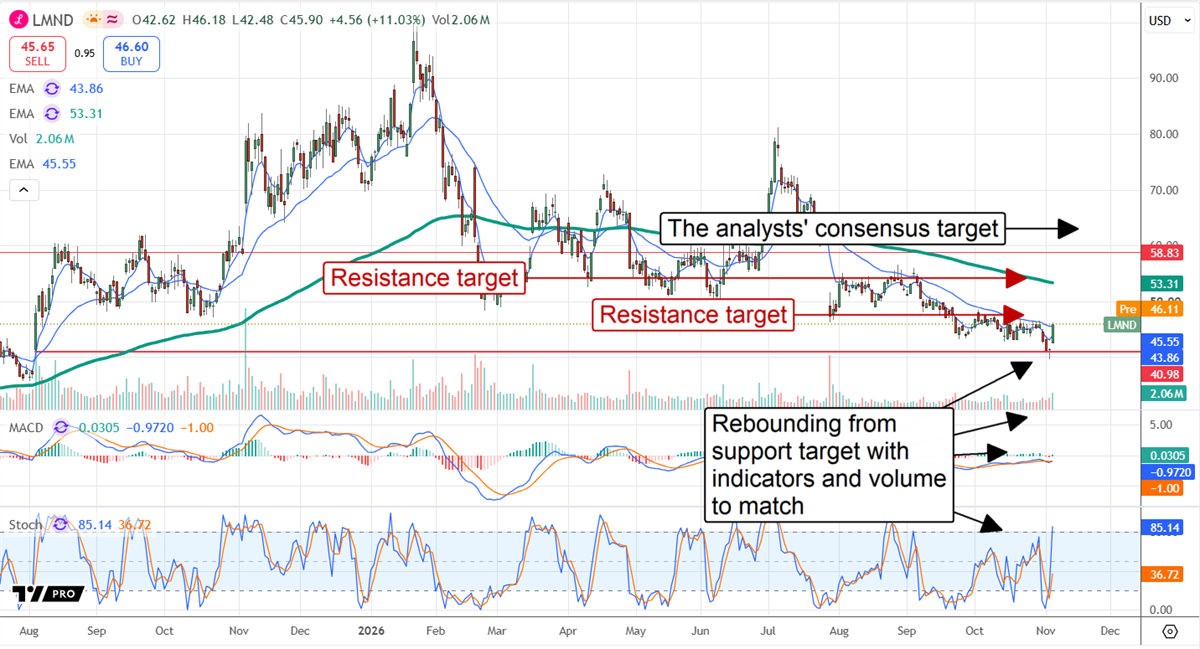
Lemonade Shares Rally Ahead of Release, Then Retreat Afterward
Lemonade’s stock price surged more than 10% ahead of the release, but fell 9.6% after the earnings report, raising questions about whether a bottom is in place. The earlier move suggested support at a 52-week low and a prior price gap, both technically strong support levels. The rebound was also accompanied by improving indicators such as MACD, stochastic, trading volume, and short interest.
MACD and stochastic had suggested that shares were oversold, pointing to waning bearish momentum and strengthening bullish momentum, although the post-earnings decline weakens that outlook. Volume is a key factor: it rose during both the rebound and the subsequent sell-off, suggesting heightened trading activity rather than confirming a bullish reversal.
Short-sellers are a significant force in this market, particularly through the potential for short-covering. Short interest topped 17% in mid-October, contributing to the stock’s downtrend. Covering is now a factor to consider and could contribute to future volume spikes. Short selling may continue to influence price action over the next quarter, so a massive upswing may not unfold yet, but covering could accelerate as subsequent reports are released.
Upside May Be Capped, Near-Term: Catalysts Lie Ahead to Clear the Way
Technical resistance targets include late-July lows near $47.25 and the long-term 150-day exponential moving average, which aligns with a congestion zone in the mid-$50s. A move to either level may trigger a bearish response, with the stronger response more likely at the EMA. However, short-sellers face risks, too. Institutions own a solid 80% of the stock and have bought on balance over the past year. Buying has been sporadic, with accumulation spikes tied to price dips, but it may become a more persistent tailwind now that profitability is in sight.
Analyst trends are tepid, which is unsurprising for a small-cap stock with no GAAP profits, but they align with the stock’s price outlook. The nine analysts MarketBeat tracks give LMND a Hold consensus rating, with four Buy ratings, four Hold ratings, and one Sell rating. The average price target of $61.13 suggests substantial upside from recent trading levels, putting the stock well above the nearest technical targets, which may be reached in 2026 or early 2027. The question is when analysts will shift to a more bullish posture, with increased coverage and improved ratings; Q4 profitability may be the trigger.
Lemonade’s primary risks are operational and technological. The company relies heavily on AI and bots across its business, which creates risks including profiling, unfair denials, and poor customer relations. Customers complain that there are too few humans to handle complex claims, contributing to a higher-than-average complaint index score. Operationally, results can be affected by underwriting changes involving higher-risk properties, such as those with aging roofs or in riskier locations.
. |


No comments:
Post a Comment