
A Message From Profits Run
Here's what changes if you wait to download my "Simple Options Trading For Beginners" book.
The book doesn't. Same pages, same plain-English explanations, same handful of techniques.
The only thing that changes is the price.
Right now, through this temporary link, it costs nothing.
After the link expires, it's $29.97 on my website. That's what it sells for most of the year.
So "I'll grab it later" isn't really a delay. It's a decision to pay $29.97 for something you could have had for nothing.
Not a great trade.
The better one takes a few seconds and happens today.
Download your copy while it's still $0.
Good Trading,
Bill Poulos
P.S. Once it's saved to your computer, the price can't reach it. That only works if you grab it before the link expires.
Special Report
Firefly Aerospace Lights Up a High-Risk Space Opportunity
Submitted by Thomas Hughes. First Published: 11/13/2026.
Key Points
- Firefly Aerospace's backlog, contract wins, and a landmark $1.3 billion AST SpaceMobile deal position it to quickly close the gap with larger rival Rocket Lab.
- Improved guidance, a Lockheed Martin launch agreement extension, and five concurrent lunar missions underscore accelerating momentum despite swelling adjusted losses.
- Shareholder dilution, government contract concentration, and recurring Alpha launch delays remain significant risks clouding Firefly's path to profitability.
- Special Report: A free stock pick, from me to you
Firefly Aerospace (NASDAQ: FLY) is still a small company, but it represents an aggressive opportunity in space development. While Q3 revenue came in at less than half of what Rocket Lab (NASDAQ: RKLB)reported for the same period, Firefly’s backlog, contract wins and expansion plans position it to catch up quickly. Investors have an opportunity to enter the market while shares remain well below earlier highs. Firefly is growing at a rapid pace, although its timeline to profitability remains uncertain.
Q3 results reflect a company executing its strategy and attracting demand. Highlights include a landmark deal with AST SpaceMobile (NASDAQ: ASTS) to provide hardware, intellectual property (IP) and support services. Valued at about $1.3 billion, the deal includes about $800 million in consideration for a license to manufacture Miranda and Vira engines, with the remainder covering engine deliveries and engineering services. The deal validates Firefly’s technology and adds to its growth prospects. Its existing backlog represents nearly four years of activity at the Q3 pace, even before accounting for the AST agreement. The deal could also reduce launch risks for AST SpaceMobile.
Firefly Aerospace Triggers Momentum Boost With Q3 Results
Firefly Aerospace’s Q3 results showed accelerating momentum, with revenue up about 260% year over year, 7.3% above expectations, and guidance improving. Revenue was driven by numerous projects, while work on five lunar missions also improved visibility. Contract wins include an extension of a multiyear launch agreement with Lockheed Martin (NYSE: LMT), providing clarity into the early next decade.
Margin news was mixed, with adjusted losses widening as the company pursued its strategy. Work included expanding a cleanroom facility that now enables the simultaneous manufacture of up to 12 lunar landers and orbital vehicles. Despite the heavy spending, adjusted losses came in a nickel below consensus.
Guidance is a catalyst. The improved outlook added to the strength of the quarter and backlog growth, coming in ahead of consensus and forecasting approximately 24% sequential growth, though it remains cautious. While launch delays are weighing on the outlook, strength in other segments, including defense software, offsets some of that impact. The five parallel lunar missions also provide a solid baseline and lay the groundwork for upside surprises.
Analysts Lift Targets: Reinforce Upside Potential for Firefly Investors
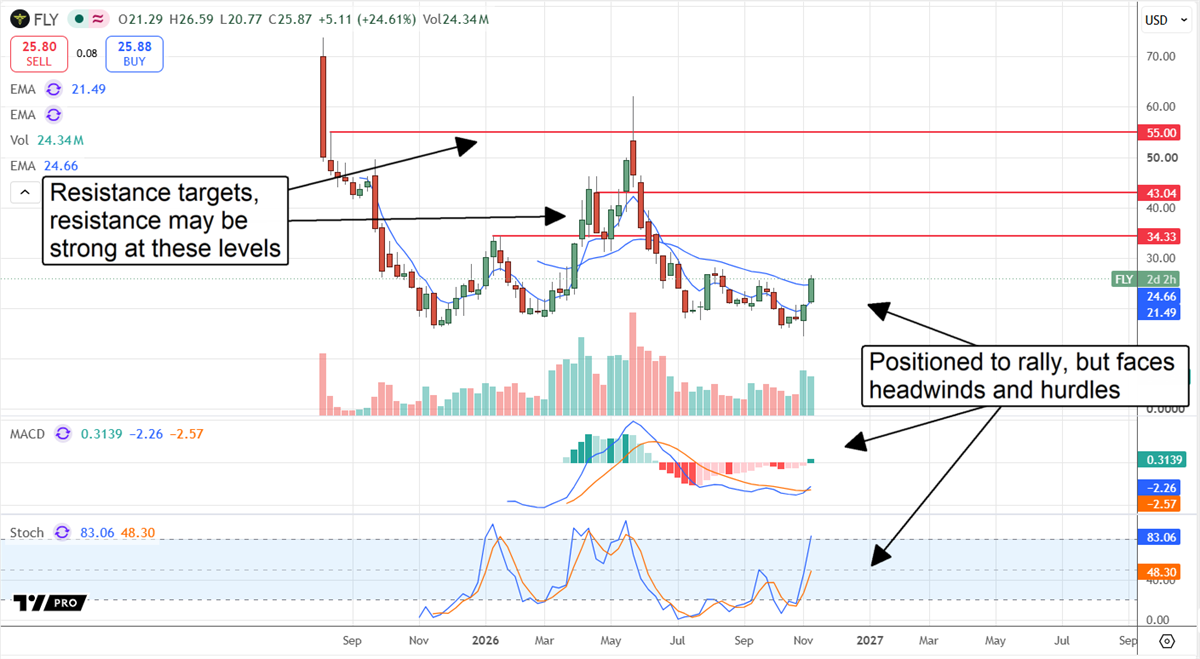
Analysts’ responses highlight the strength of Firefly’s quarter, with several firms raising price targets after the report. Commentary focused on the earnings beat, backlog and guidance, along with the validating AST SpaceMobile deal. The target range is wide, but Firefly has a Moderate Buy consensus rating and an average price target of $35.75, suggesting about 50% upside from recent trading levels. The expectation is now for Firefly to continue executing its strategy and sustain its cycle of positive revisions.
Price action was bullish following the release, with shares rising more than 10% and suggesting a potential market bottom. Whether this is the absolute bottom remains to be seen. Near-term signals suggest upside potential, but technical hurdles remain. Prior highs near $35, along with a congestion band in the $35 to $45 region, may provide enough resistance to cap gains.
There Are Plenty of Risks and Headwinds for Firefly Shareholders
Risks include, but are not limited to, shareholder dilution. Q3 highlights show a well-capitalized company with limited debt and steady equity, but cash is down year to date despite a dilutive capital raise, and the cash bonfire is still burning. Cash could continue to dwindle, increasing dilution risk until the company reaches profitability. Based on Q3 figures, additional financing remains a risk before that transition. News of capital-raising activity could create selling pressure.
Other risks center on concentration and execution. Firefly Aerospace’s outlook is rapidly improving, but its existing revenue and backlog are tied to a few government entities, while the new AST SpaceMobile agreement introduces additional execution risks. Government contracts are exposed to budget shifts and changes in administration, while ASTS is an equally speculative play on space-based 5G services with no guarantee of success. The Alpha launch system has experienced several setbacks and delays, with the next launch not slated until early 2027. Governance is also a risk, as a large shareholder retains significant influence over the company.
Boiled down, bulls may be getting the timeline to scale wrong. Project delays, rising costs and widening adjusted losses cloud the outlook and make the existing timeline uncertain at best. Bears may be wrong to treat Firefly like a pure launch company, because its primary revenue source and growth drivers are spacecraft solutions, including vehicles and defense software. While launch matters, the five concurrent lunar missions and the vehicle requirements they bring are the bigger story. In addition, acquiring SciTec embeds Firefly in the defense software industry.
. |


No comments:
Post a Comment